In a market where mortgage interest rates remain significantly higher than they were just a few years ago, assumable loans have become an increasingly attractive option for homebuyers. An assumable loan allows a purchaser to take over the seller’s existing mortgage, including the remaining balance, interest rate, repayment schedule, and loan terms. Rather than obtaining a brand-new mortgage at current market rates, the buyer steps into the seller’s loan and continues making payments under the existing financing arrangement. For buyers, this can represent a substantial financial advantage, particularly when the seller secured a mortgage during the historically low interest rate environment of 2020 through 2022.
Not every mortgage is assumable. Most conventional loans originated through traditional lending programs contain due-on-sale clauses that require the loan to be paid in full when ownership transfers. However, many loans insured or guaranteed by government-backed programs are assumable, including FHA, VA, and USDA loans. Before investing significant time in negotiations, buyers should confirm with the seller and loan servicer that the mortgage is in fact assumable and determine the lender’s specific requirements for approving the transaction.
The greatest appeal of an assumable loan is often the interest rate. Consider a seller who obtained a mortgage at 2.75% in 2021. If current mortgage rates are closer to 6.5%, assuming the seller’s loan could reduce a buyer’s monthly payment by hundreds of dollars. Over the life of the loan, the savings can amount to tens or even hundreds of thousands of dollars. In many situations, the ability to acquire a low-rate mortgage can be just as valuable as purchasing a property at a lower price.
While the concept sounds simple, assumable loans present a unique challenge known as the “equity gap.” The seller’s remaining mortgage balance is often much lower than the property’s current market value. For example, a home selling for $900,000 may have an assumable loan balance of only $550,000. The buyer must somehow provide the remaining $350,000 needed to complete the purchase. Some buyers accomplish this through a large cash down payment, while others utilize secondary financing or funds from the sale of another property. The larger the difference between the purchase price and the existing loan balance, the more difficult the transaction may become.
Many buyers are surprised to learn that assuming a loan still requires lender approval. The lender will generally review the buyer’s credit history, income, employment, assets, and debt obligations in much the same way as it would for a new mortgage application. The lender wants to ensure that the new borrower has the financial ability to make the loan payments. Although the buyer is taking over an existing loan rather than applying for a new one, qualification standards still apply.
Timing is another important consideration. Assumptions frequently take longer than traditional mortgage transactions. Some lenders have dedicated assumption departments, while others process relatively few assumptions each year. As a result, approval timelines can range from several weeks to several months. Buyers and sellers should anticipate a longer escrow period and ensure that contract deadlines provide sufficient time for the lender to complete its review.
VA loans require additional attention because of the potential impact on the seller’s VA entitlement. In some situations, if a non-veteran assumes the loan, the seller’s entitlement may remain tied to the property until the loan is paid off or refinanced. Veteran sellers should consult with the lender regarding entitlement restoration before agreeing to an assumption, as this issue may affect their ability to utilize VA financing in the future.
For buyers evaluating an assumable loan opportunity, it is important to obtain detailed information regarding the mortgage. Questions should include the current loan balance, interest rate, monthly payment, escrow requirements, loan servicer, and the lender’s current assumption process. A low interest rate may appear attractive at first glance, but the transaction must still make financial sense when considering the cash required to bridge the gap between the loan balance and the purchase price.
In today’s market, assumable loans can provide a significant competitive advantage. Buyers who have sufficient cash reserves or access to secondary financing may find that assuming a low-rate FHA, VA, or USDA mortgage allows them to purchase a property with substantially lower monthly payments than would otherwise be possible. For sellers, advertising an assumable mortgage can attract additional buyer interest and help distinguish a property from competing listings. When structured properly, an assumable loan can create benefits for both parties and serve as a valuable tool in achieving a successful real estate transaction. If you have questions on finding and acquiring a property with an assumable loan in the San Francisco East Bay, contact Derek Wagley Broker Associate at Keller Williams Realty at 925-451-6679.
Search all Recent Alameda County Condo Price Reductions
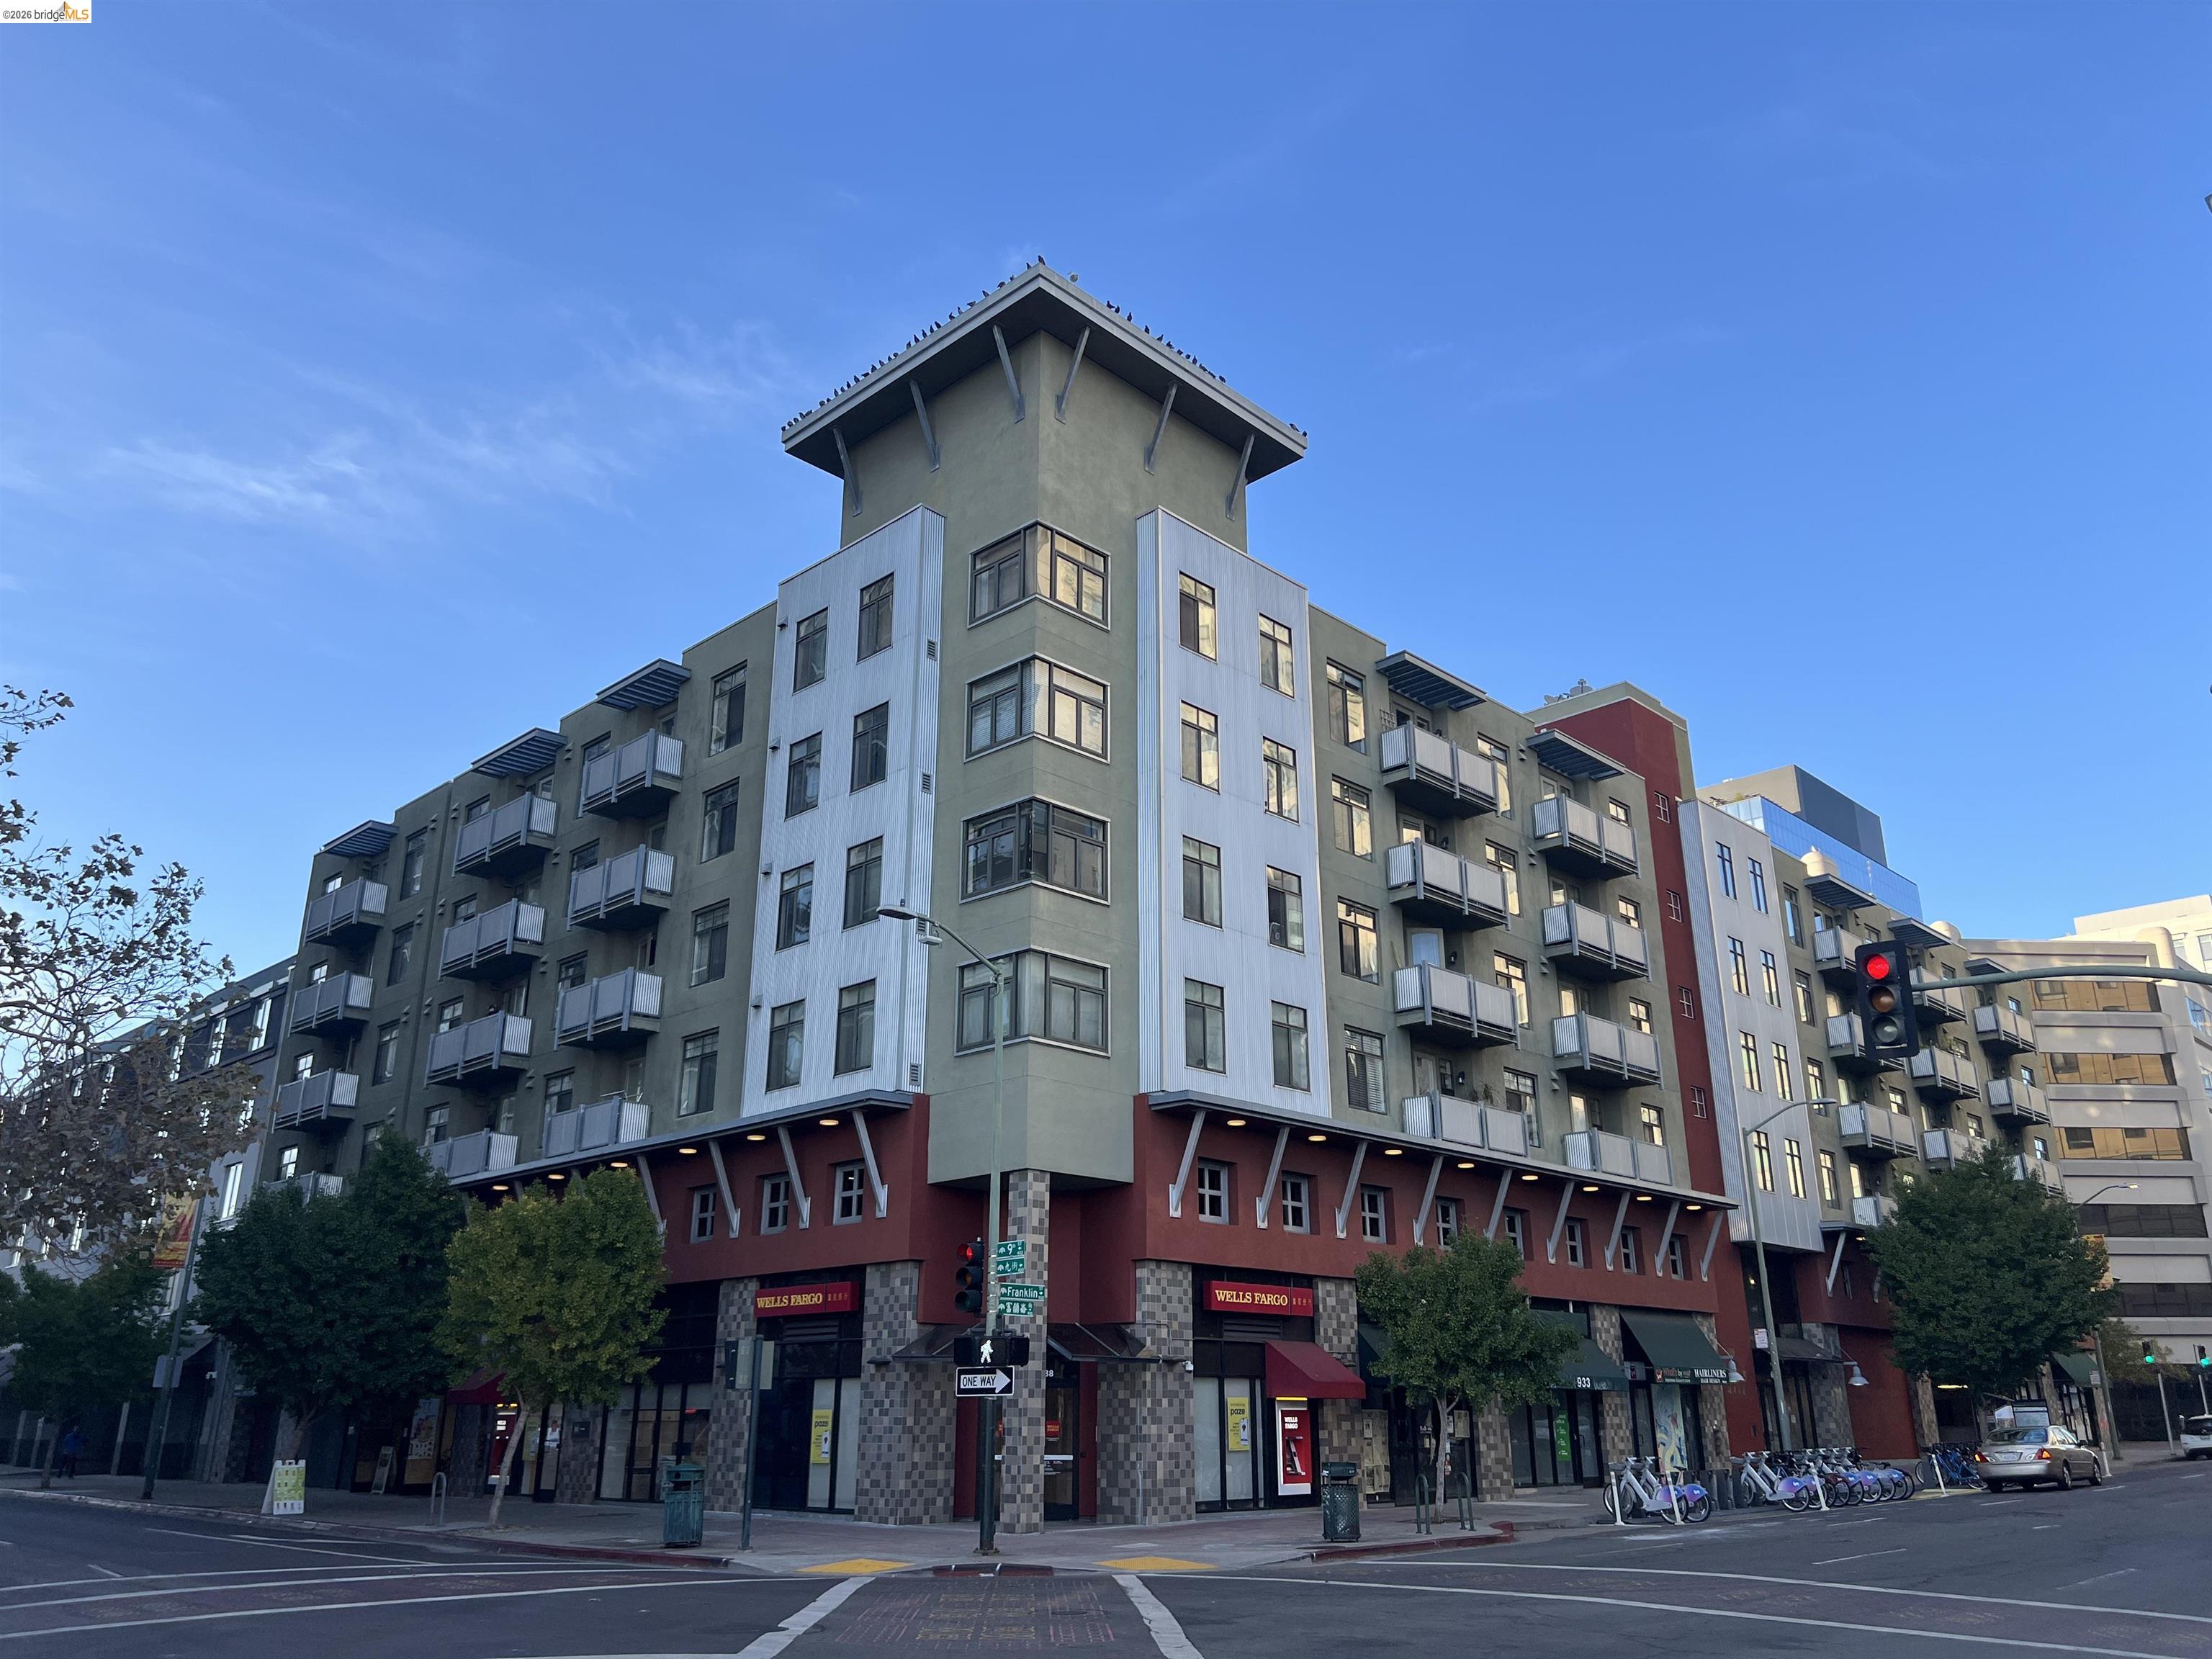 $288,000
Active
989 Franklin Street 307 Oakland, California
1 Beds 1 Baths 533 SqFt
 $299,000
Active
2522 Copa Del Oro Drive Union City, California
1 Beds 1 Baths 590 SqFt 3.006 Acres
 $299,000
Active
3877 Howe Street 108 Oakland, California
1 Beds 1 Baths 622 SqFt
 $308,000
Active
989 Franklin Street 506 Oakland, California
1 Beds 1 Baths 524 SqFt 0.044 Acres
 $349,000
Active
955 Shorepoint Ct 100 Alameda, California
1 Beds 1 Baths 773 SqFt 2.325 Acres
 $365,000
Active
3655 Birchwood Ter 112 Fremont, California
1 Beds 1 Baths 714 SqFt
 $375,000
Active
1920 Union St 9 Oakland, California
1 Beds 1 Baths 1,006 SqFt 0.41 Acres
 $379,000
Active
7 Embarcadero West 207 Oakland, California
1 Beds 1 Baths 885 SqFt
 $386,000
Active
38500 Paseo Padre Pkwy 313 Fremont, California
1 Beds 1 Baths 750 SqFt 4.253 Acres
 $388,888
Active
7750 Canyon Meadow Circle G Pleasanton, California
2 Beds 2 Baths 1,043 SqFt
 $389,000
Active
8 Captain Drive E356 Emeryville, California
1 Beds 1 Baths 728 SqFt 1.876 Acres
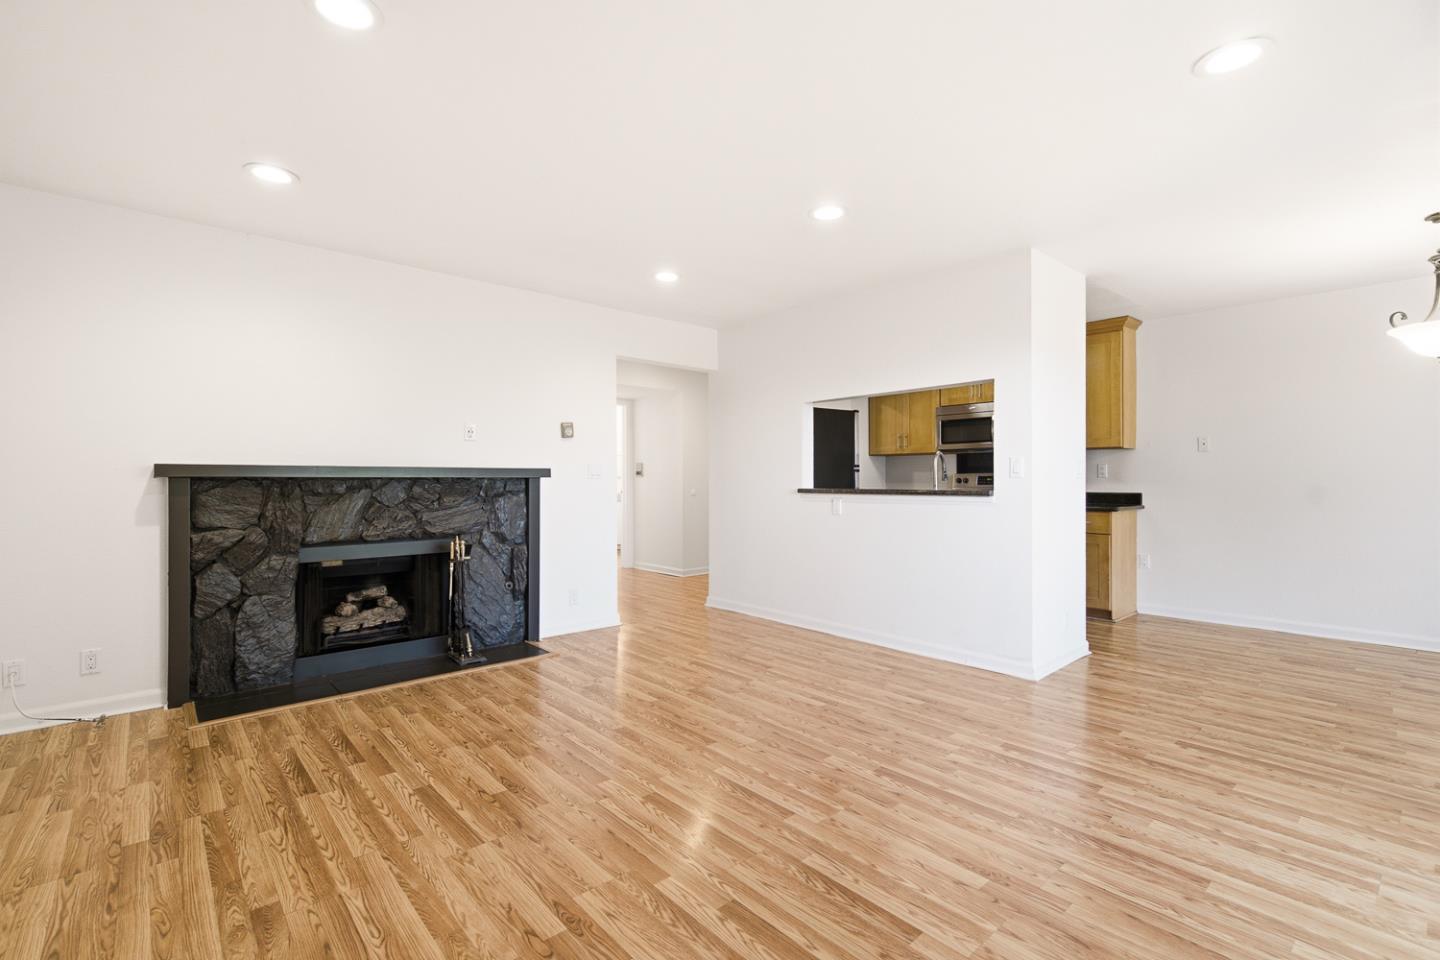 $398,000
Active
21062 Gary Drive 102 Hayward, California
1 Beds 1 Baths 815 SqFt
 $399,000
Active
27787 Vasona Ct 13 Hayward, California
1 Beds 1 Baths 874 SqFt 1.595 Acres
 $425,000
Active
19100 Crest Ave 24 Castro Valley, California
2 Beds 1 Baths 1,190 SqFt
 $439,000
Active
201 4Th St 302 Oakland, California
1 Beds 1 Baths 1,036 SqFt 0.345 Acres
 $448,000
Active
894 Lewelling Blvd 13 San Leandro, California
2 Beds 1 Baths 858 SqFt 0.954 Acres
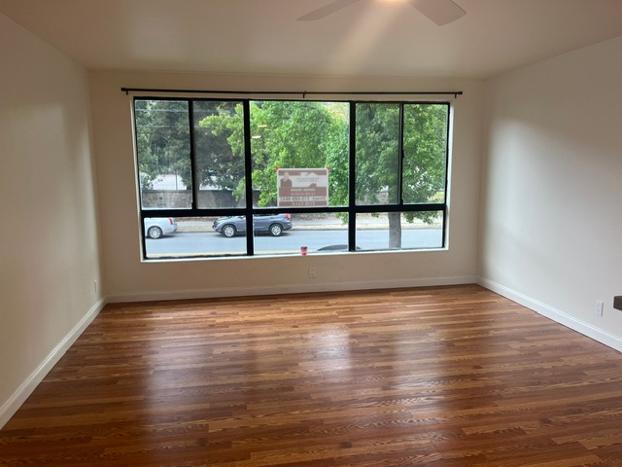 $448,888
Active
2632 Warring Street 2 Berkeley, California
2 Beds 1 Baths 845 SqFt 0.001 Acres
 $450,000
Active
2125 Arroyo Ct 2 Pleasanton, California
2 Beds 1 Baths 903 SqFt
 $482,888
Active
1121 40th ST 5102 Emeryville, California
2 Beds 2 Baths 758 SqFt
 $485,000
Active
1021 Santa Ines Ct Oakland, California
3 Beds 2 Baths 1,306 SqFt 0.021 Acres
 $494,000
Active
1315 A St 206 Hayward, California
2 Beds 2 Baths 1,056 SqFt
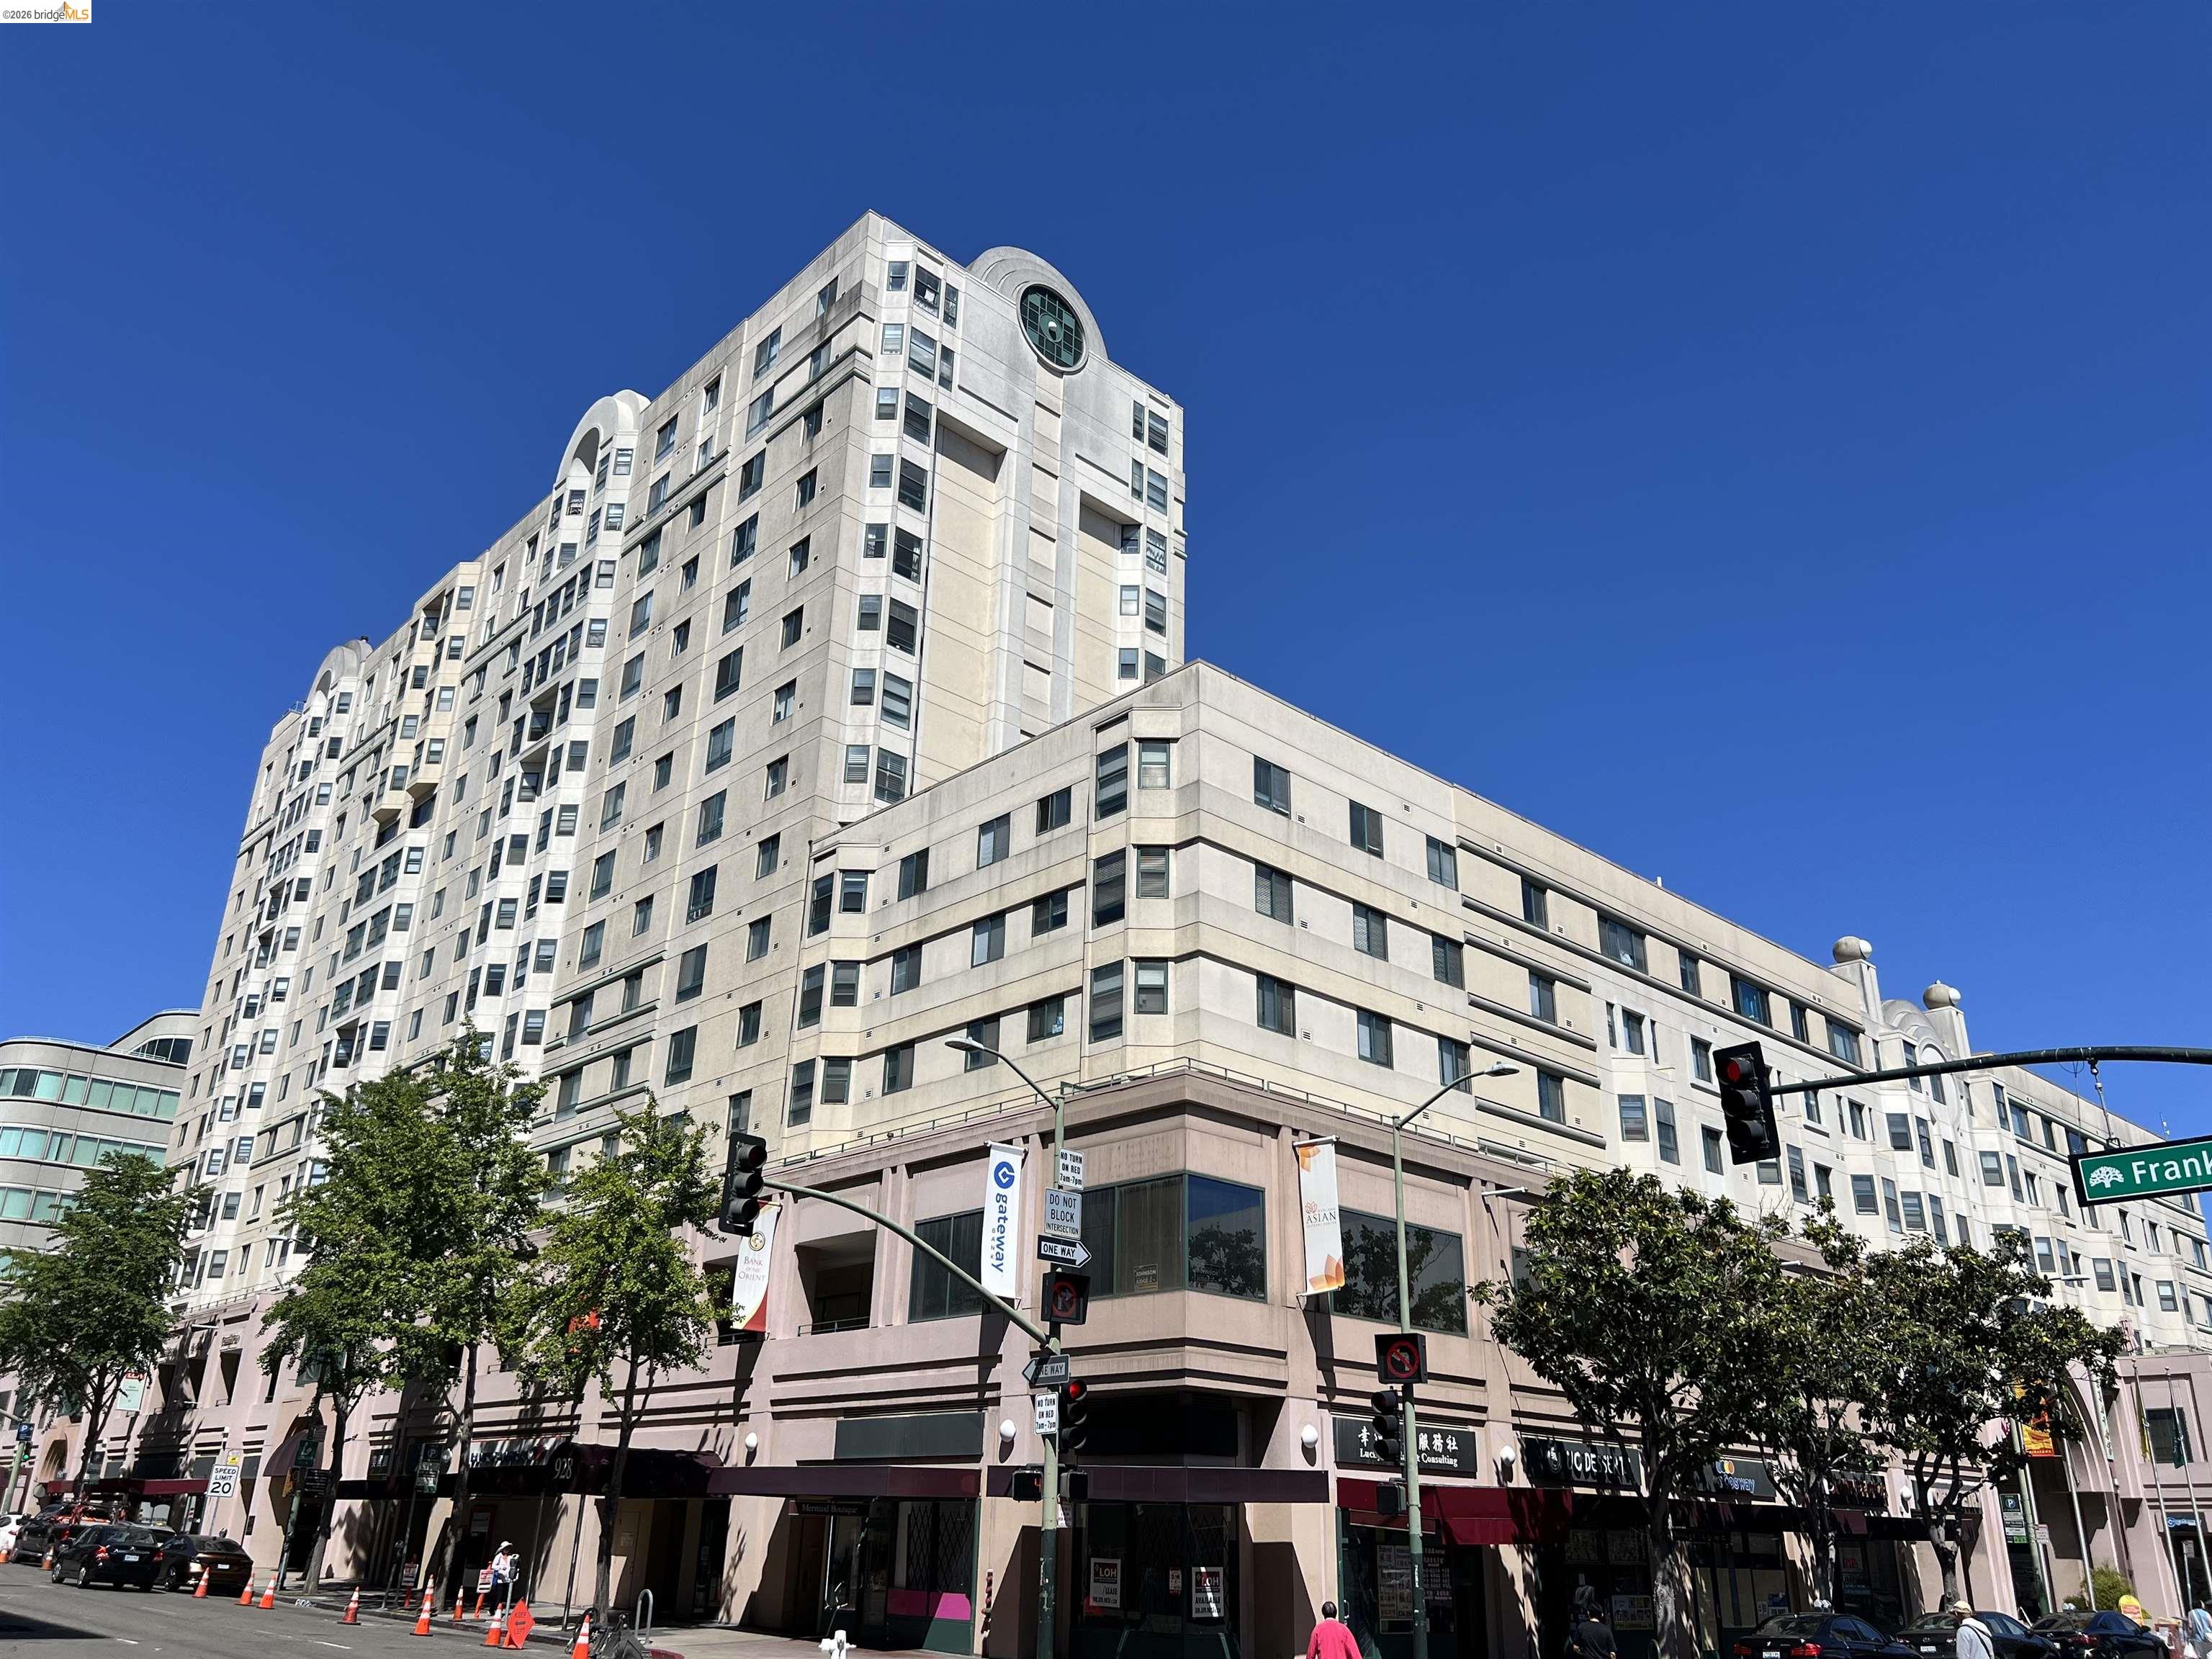 $495,000
Active
988 Franklin Street 1111 Oakland, California
2 Beds 2 Baths 898 SqFt 2.25 Acres
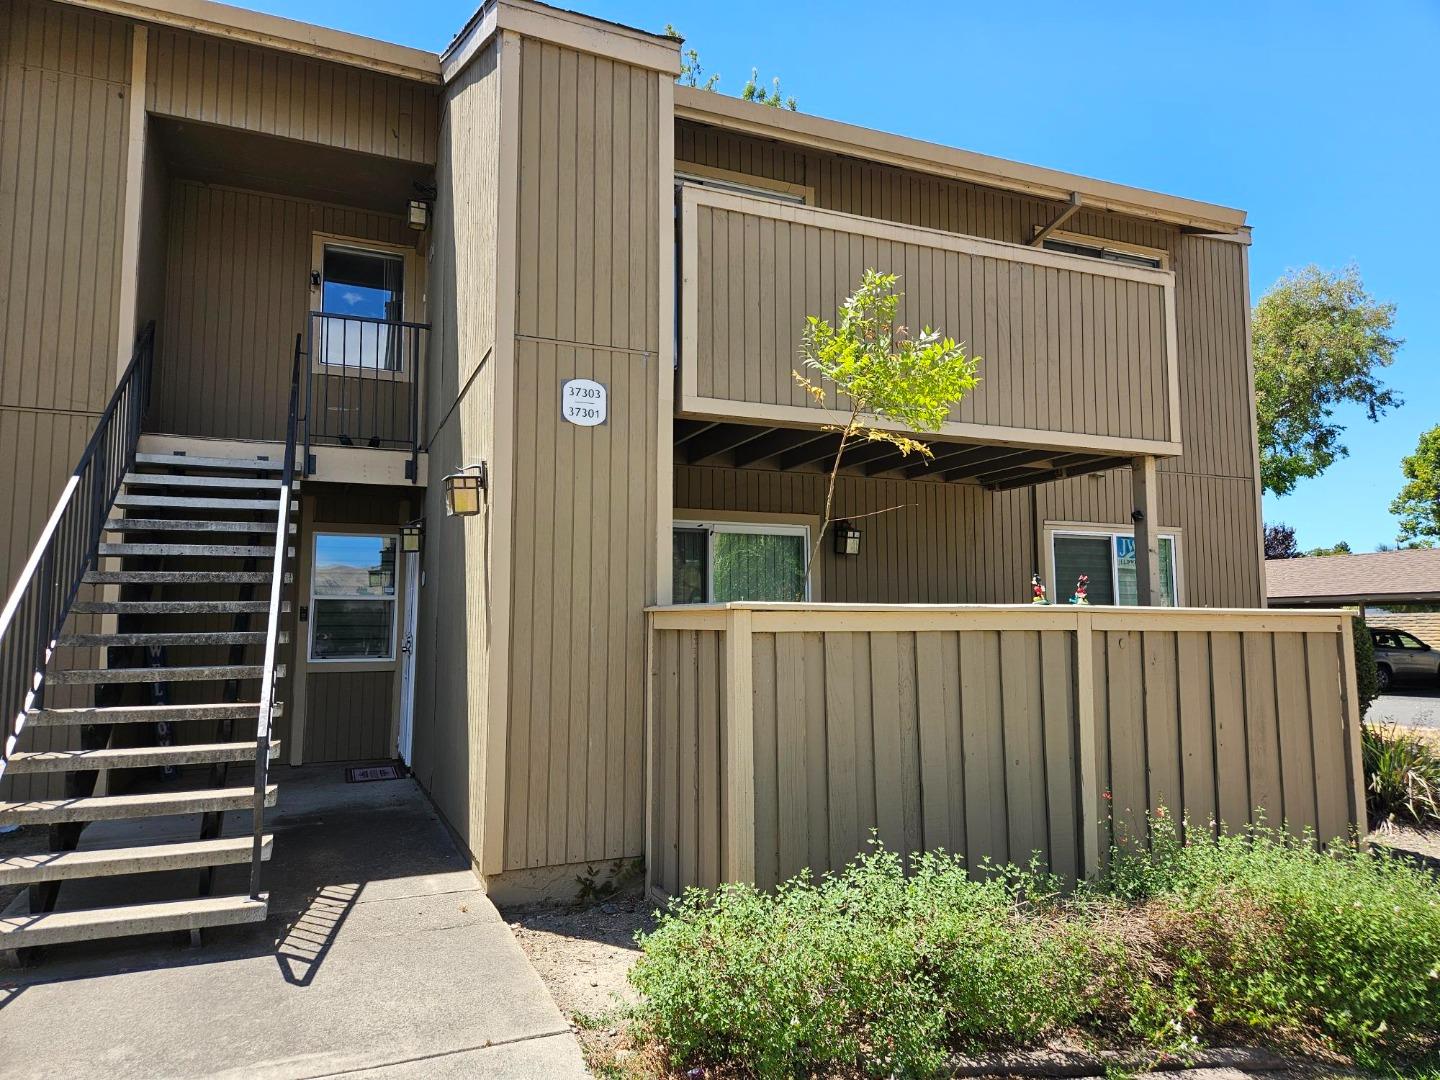 $495,000
Active
37303 Sequoia Road Fremont, California
2 Beds 2 Baths 840 SqFt
 $498,000
Active
3090 Glascock St 303 Oakland, California
2 Beds 2 Baths 1,133 SqFt 1.147 Acres
 $499,000
Active
423 7th Street 313 Oakland, California
2 Beds 2 Baths 1,235 SqFt 0.75 Acres
 $499,000
Active
29588 Vanderbilt St 316 Hayward, California
2 Beds 2 Baths 894 SqFt
 $499,000
Active
20278 Forest Ave 4 Castro Valley, California
2 Beds 1 Baths 1,014 SqFt 0.492 Acres
 $510,000
Active
7650 Canyon Meadows Cir F Pleasanton, California
2 Beds 2 Baths 1,043 SqFt
 $515,000
Active
960 Shorepoint Ct 120 Alameda, California
2 Beds 2 Baths 1,152 SqFt 3.071 Acres
 $545,000
Active
2322 Belvedere Ave San Leandro, California
2 Beds 1 Baths 1,108 SqFt 0.019 Acres
 $565,000
Active
1815 Second Street Alameda, California
3 Beds 1 Baths 980 SqFt
 $569,000
Active
1500 Alameda D Alameda, California
2 Beds 2 Baths 1,002 SqFt 0.269 Acres
 $570,000
Active
38623 Cherry Ln 121 Fremont, California
2 Beds 1 Baths 929 SqFt 14.904 Acres
 $588,000
Active
535 Pierce ST #3109 Albany, California
2 Beds 2 Baths 1,170 SqFt
 $595,000
Active
2725 Prince St. 10 Berkeley, California
2 Beds 1 Baths 776 SqFt 0.243 Acres
 $595,000
Active
4408 Comanche Way Pleasanton, California
2 Beds 1 Baths 988 SqFt 0.018 Acres
 $599,000
Active
7595 Canyon Meadow Circle H Pleasanton, California
3 Beds 2 Baths 1,257 SqFt
 $599,000
Active
4664 Devonshire Cmn Fremont, California
2 Beds 2 Baths 945 SqFt 0.033 Acres
 $599,000
Active
3300 Wolcott Cmn 113 Fremont, California
2 Beds 2 Baths 1,013 SqFt 0.292 Acres
 $599,000
Active
1119 Hearst Ave Berkeley, California
1 Beds 1 Baths 824 SqFt 0.115 Acres
 $599,800
Active
1547 Chandler St Oakland, California
3 Beds 2 Baths 1,734 SqFt 0.305 Acres
 $618,888
Active
4074 Gibraltar Drive Fremont, California
2 Beds 1 Baths 988 SqFt
 $619,900
Active
260 Brooklyn Basin Way 533 Oakland, California
3 Beds 2 Baths 1,250 SqFt
 $625,000
Active
17994 Azalea Rd. Hayward, California
2 Beds 2 Baths 1,270 SqFt 17.7 Acres
 $629,000
Active
3474 Smoketree Commons Dr D Pleasanton, California
2 Beds 2 Baths 938 SqFt
 $635,000
Active
200 Cypress St Alameda, California
3 Beds 1 Baths 1,120 SqFt
 $649,000
Active
322 Hanover Ave 512 Oakland, California
2 Beds 2 Baths 1,005 SqFt 0.75 Acres
 $649,888
Active
10837 Mcpeak Ln Dublin, California
2 Beds 2 Baths 1,103 SqFt
 $650,000
Active
5501 De Marcus Blvd 218 Dublin, California
2 Beds 2 Baths 1,088 SqFt
 $659,000
Active
25084 Vista Greens Ct Hayward, California
2 Beds 2 Baths 1,250 SqFt 0.044 Acres
 $660,000
Active
3419 Pennsylvania Cmn Fremont, California
2 Beds 2 Baths 944 SqFt 0.039 Acres
 $669,999
Active
38737 Aurora Terrace 19 Fremont, California
2 Beds 1 Baths 1,120 SqFt
 $674,000
Active
7552 Silvertree Ln 25 Dublin, California
3 Beds 2 Baths 1,242 SqFt
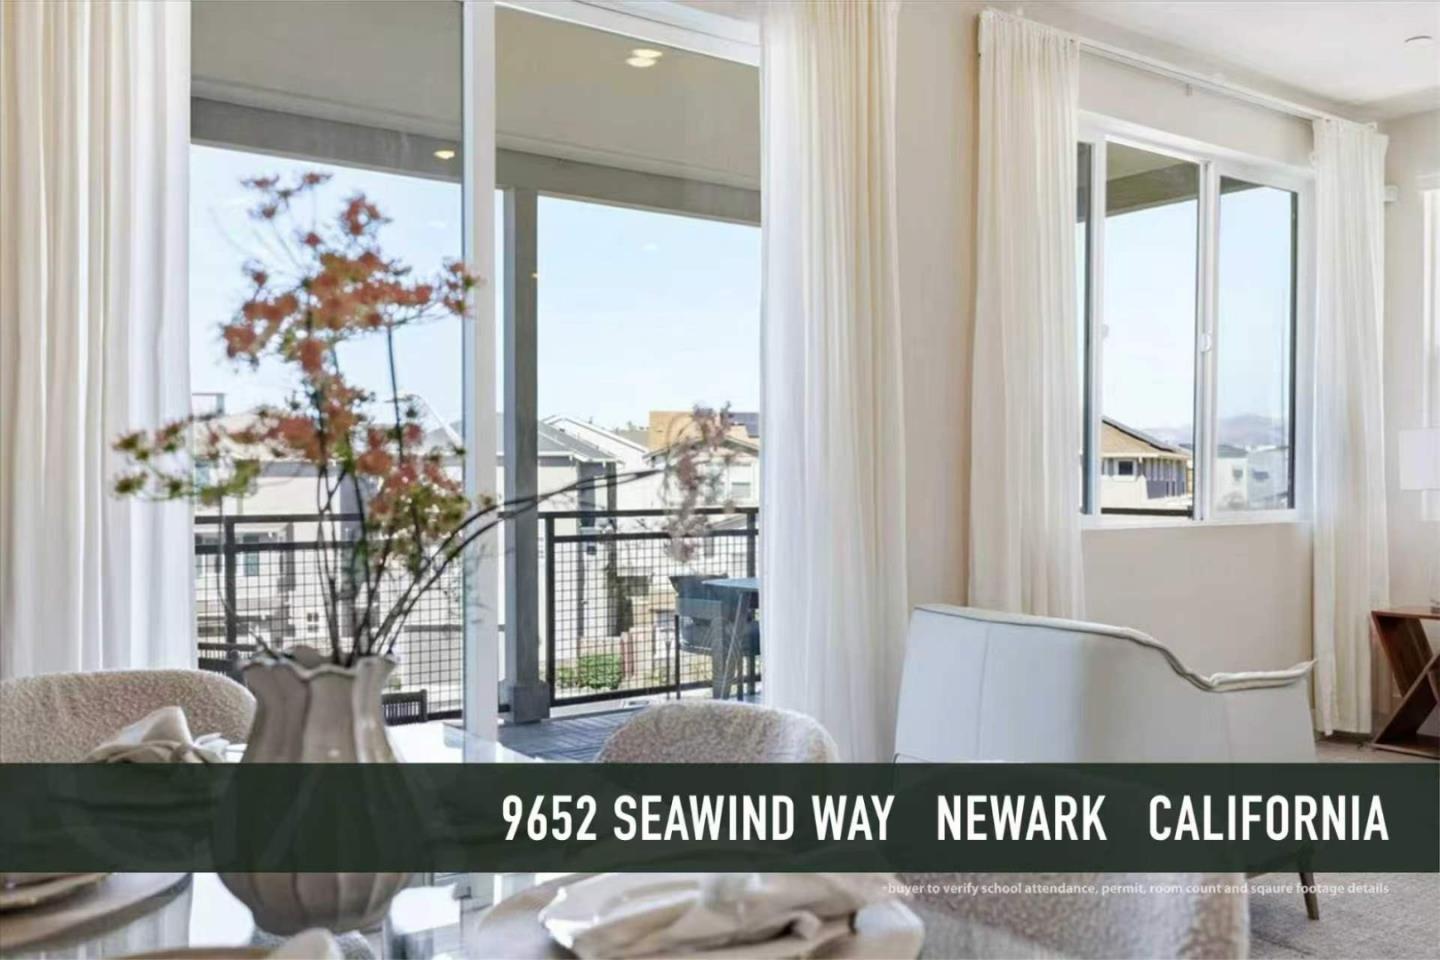 $680,000
Active
9652 Seawind Way Newark, California
2 Beds 2 Baths 1,461 SqFt
 $689,000
Active
6363 Christie Ave 326 Emeryville, California
2 Beds 2 Baths 1,369 SqFt 5.14 Acres
 $699,000
Active
5029 Shalimar Circle Fremont, California
2 Beds 2 Baths 934 SqFt
 $699,900
Active
6001 Joaquin Murieta Ave C Newark, California
3 Beds 2 Baths 1,408 SqFt
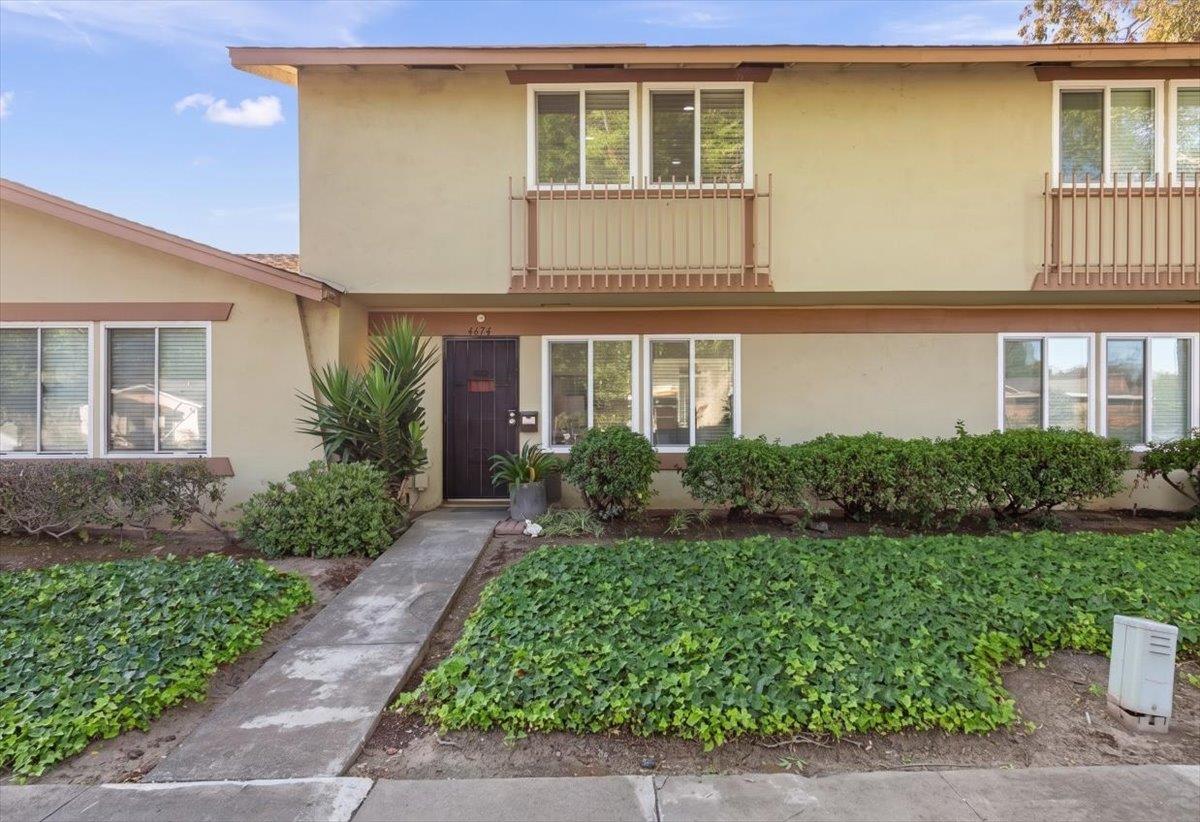 $699,950
Active
4674 Balboa Way Fremont, California
3 Beds 1 Baths 1,166 SqFt 0.02 Acres
 $699,999
Active
3153 Cochise Way Pleasanton, California
3 Beds 1 Baths 1,132 SqFt 0.021 Acres
 $708,888
Active
38030 Dundee Common Fremont, California
3 Beds 1 Baths 1,168 SqFt
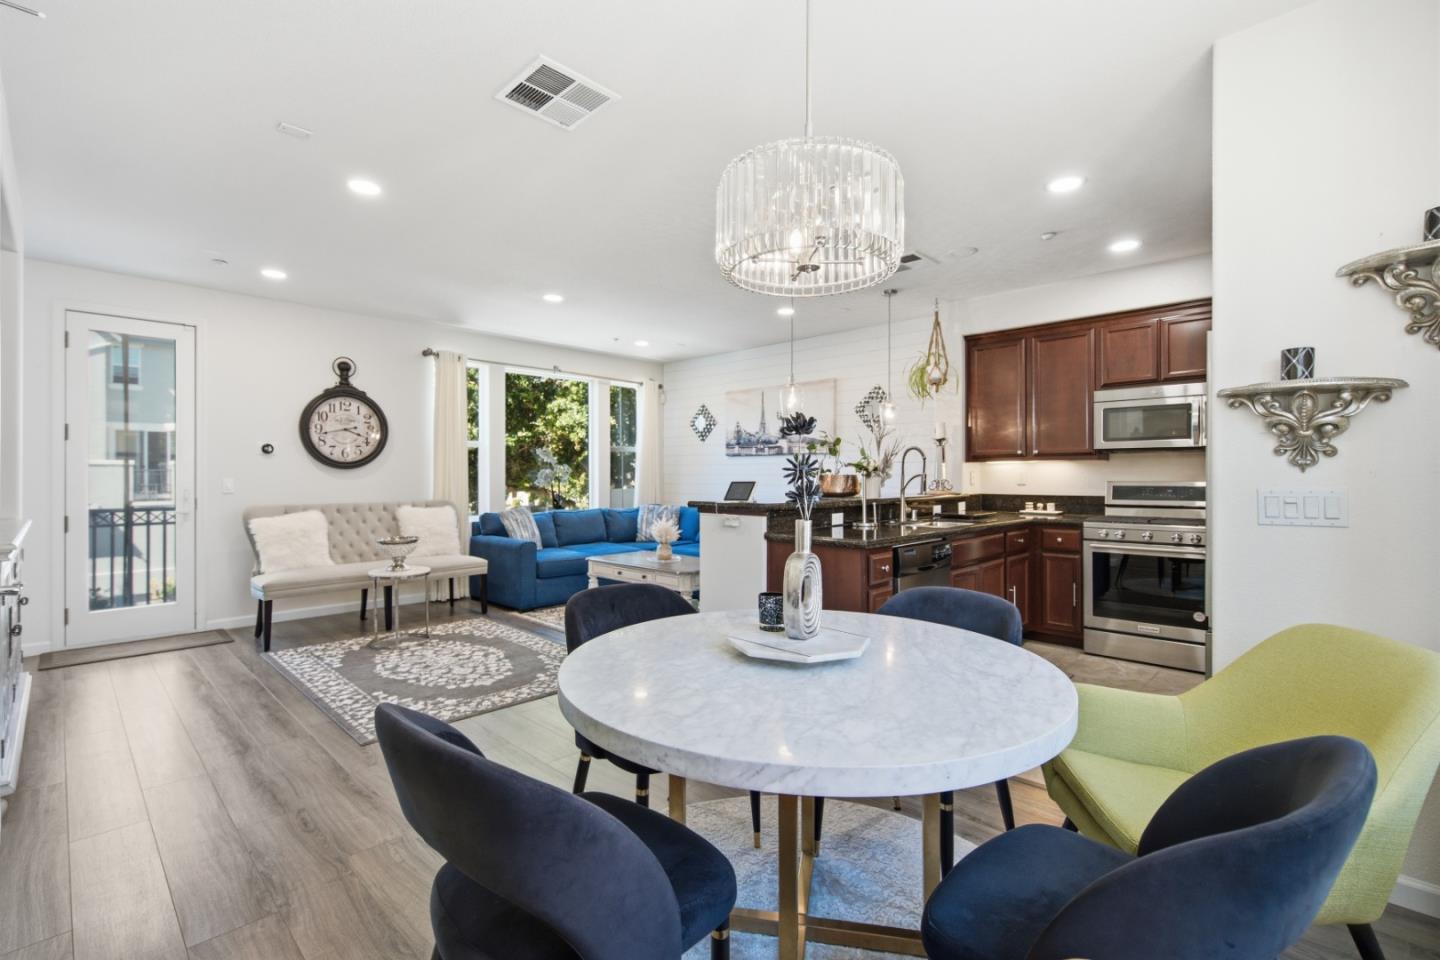 $715,000
Active
Livermore, California
2 Beds 2 Baths 1,138 SqFt 0.026 Acres
 $715,000
Active
34563 Pueblo Ter Fremont, California
2 Beds 2 Baths 840 SqFt 3.43 Acres
 $715,000
Active
3861 Vine St Pleasanton, California
2 Beds 2 Baths 1,221 SqFt 0.025 Acres
 $720,000
Active
1721 18th Street Oakland, California
3 Beds 3 Baths 1,584 SqFt
 $725,000
Active
34598 Pueblo Terrace Fremont, California
2 Beds 2 Baths 918 SqFt
 $725,000
Active
38738 Huntington Circle Fremont, California
2 Beds 2 Baths 1,168 SqFt
 $729,000
Active
2029 Channing Way 3D Berkeley, California
2 Beds 1 Baths 803 SqFt 0.221 Acres
 $749,000
Active
438 W Grand Ave 418 Oakland, California
2 Beds 2 Baths 1,471 SqFt 0.029 Acres
 $749,999
Active
1137 Kottinger Dr CA3 Pleasanton, California
2 Beds 2 Baths 1,048 SqFt
 $749,999
Active
25320 Villager Lane Hayward, California
2 Beds 2 Baths 1,445 SqFt
 $750,000
Active
2 Panoramic Way 105 Berkeley, California
2 Beds 1 Baths 835 SqFt 0.185 Acres
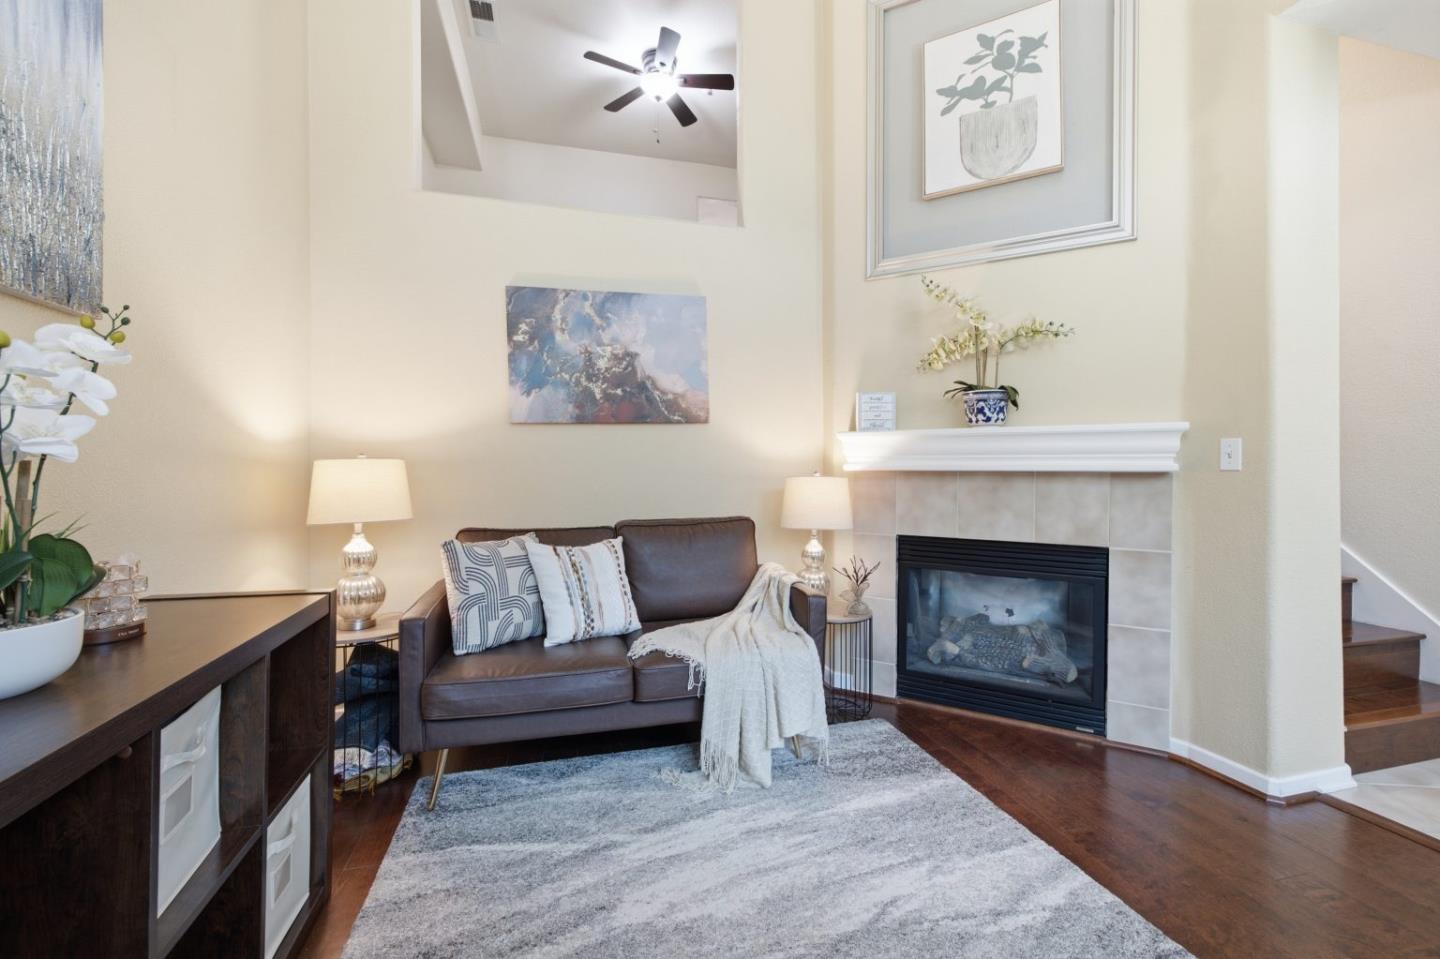 $750,000
Active
22859 Charing Street Hayward, California
2 Beds 2 Baths 1,524 SqFt 0.03 Acres
 $750,000
Active
417 Evelyn Avenue 302 Albany, California
3 Beds 2 Baths 1,170 SqFt 0.348 Acres
 $750,000
Active
29272 Hub Lane Hayward, California
2 Beds 2 Baths 1,558 SqFt 1.619 Acres
 $755,000
Active
123 Northwood Cmns Livermore, California
3 Beds 2 Baths 1,442 SqFt 0.058 Acres
 $759,999
Active
152 Heligan Lane 15 Livermore, California
2 Beds 2 Baths 1,167 SqFt
 $769,000
Active
11651 Rolling Hills Pl Dublin, California
2 Beds 2 Baths 1,130 SqFt 0.055 Acres
 $774,000
Active
7896 Gate Way Dublin, California
3 Beds 2 Baths 1,482 SqFt 0.031 Acres
 $775,000
Active
1147 Martin Luther King Dr Hayward, California
3 Beds 2 Baths 1,704 SqFt 0.165 Acres
 $780,000
Active
7422 Oxford Cir Dublin, California
2 Beds 2 Baths 1,110 SqFt
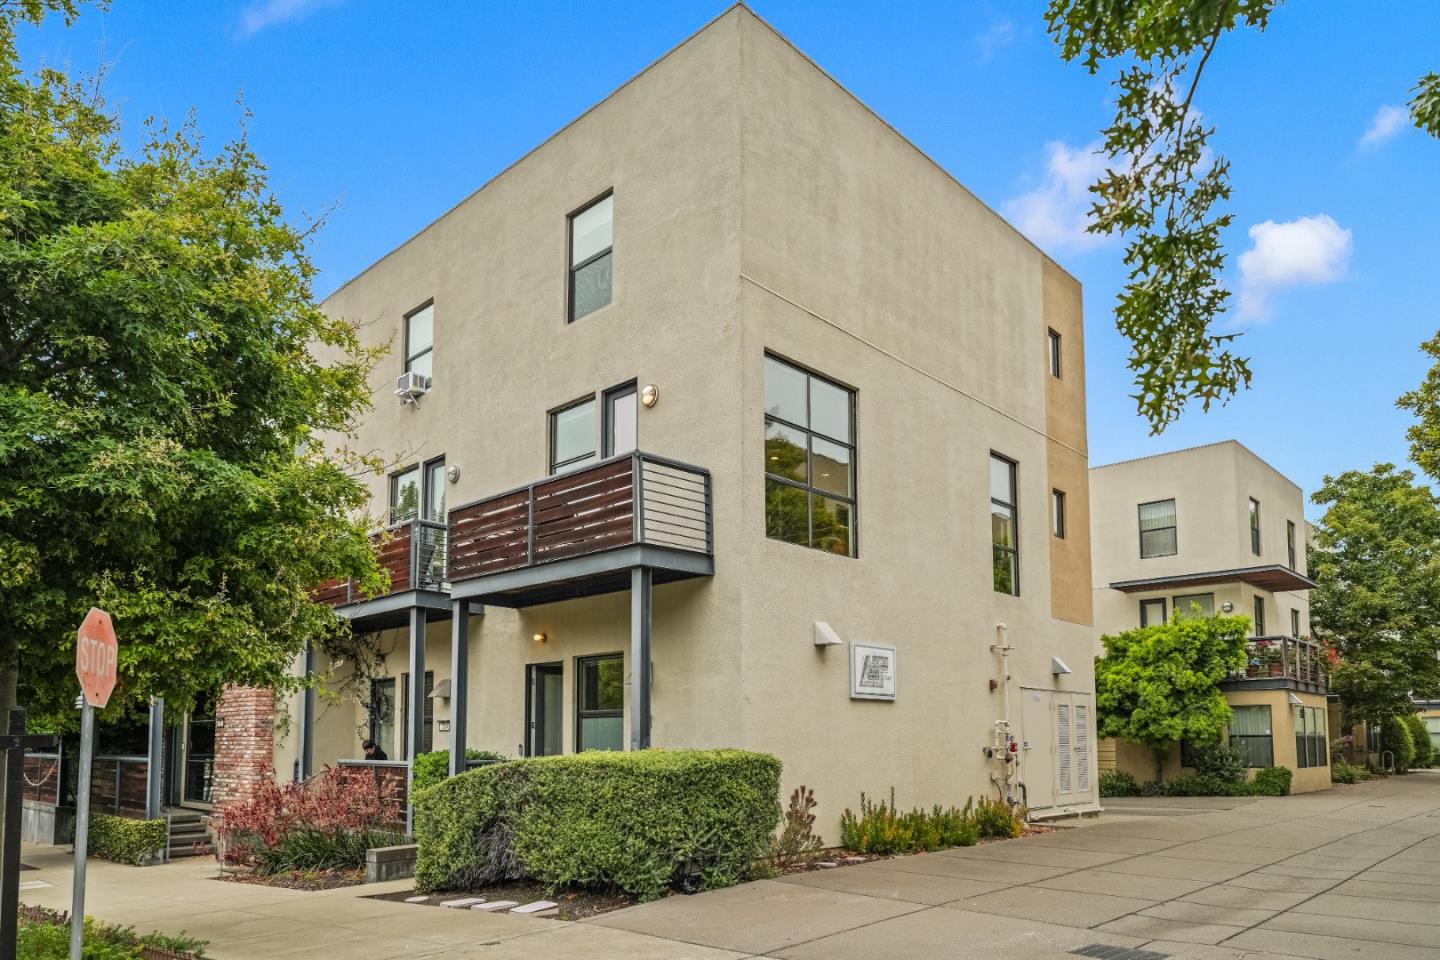 $795,000
Active
1202 66th Street Oakland, California
2 Beds 2 Baths 1,246 SqFt
 $795,000
Active
641 Centre Ct Alameda, California
3 Beds 2 Baths 1,720 SqFt 1.42 Acres
 $799,888
Active
2334 Morrow St Hayward, California
3 Beds 2 Baths 1,809 SqFt
 $799,950
Active
10706 Ian Ln Dublin, California
2 Beds 2 Baths 1,387 SqFt
 $800,000
Active
7 Courageous Ct D52 Alameda, California
2 Beds 2 Baths 1,387 SqFt 0.469 Acres
 $819,000
Active
1056 martin luther king dr. Hayward, California
3 Beds 3 Baths 1,845 SqFt
 $839,999
Active
24 Meritage Cmn 1403 Livermore, California
3 Beds 2 Baths 1,514 SqFt
 $848,000
Active
200 Lakeside 105 Oakland, California
2 Beds 1 Baths 1,382 SqFt 0.789 Acres
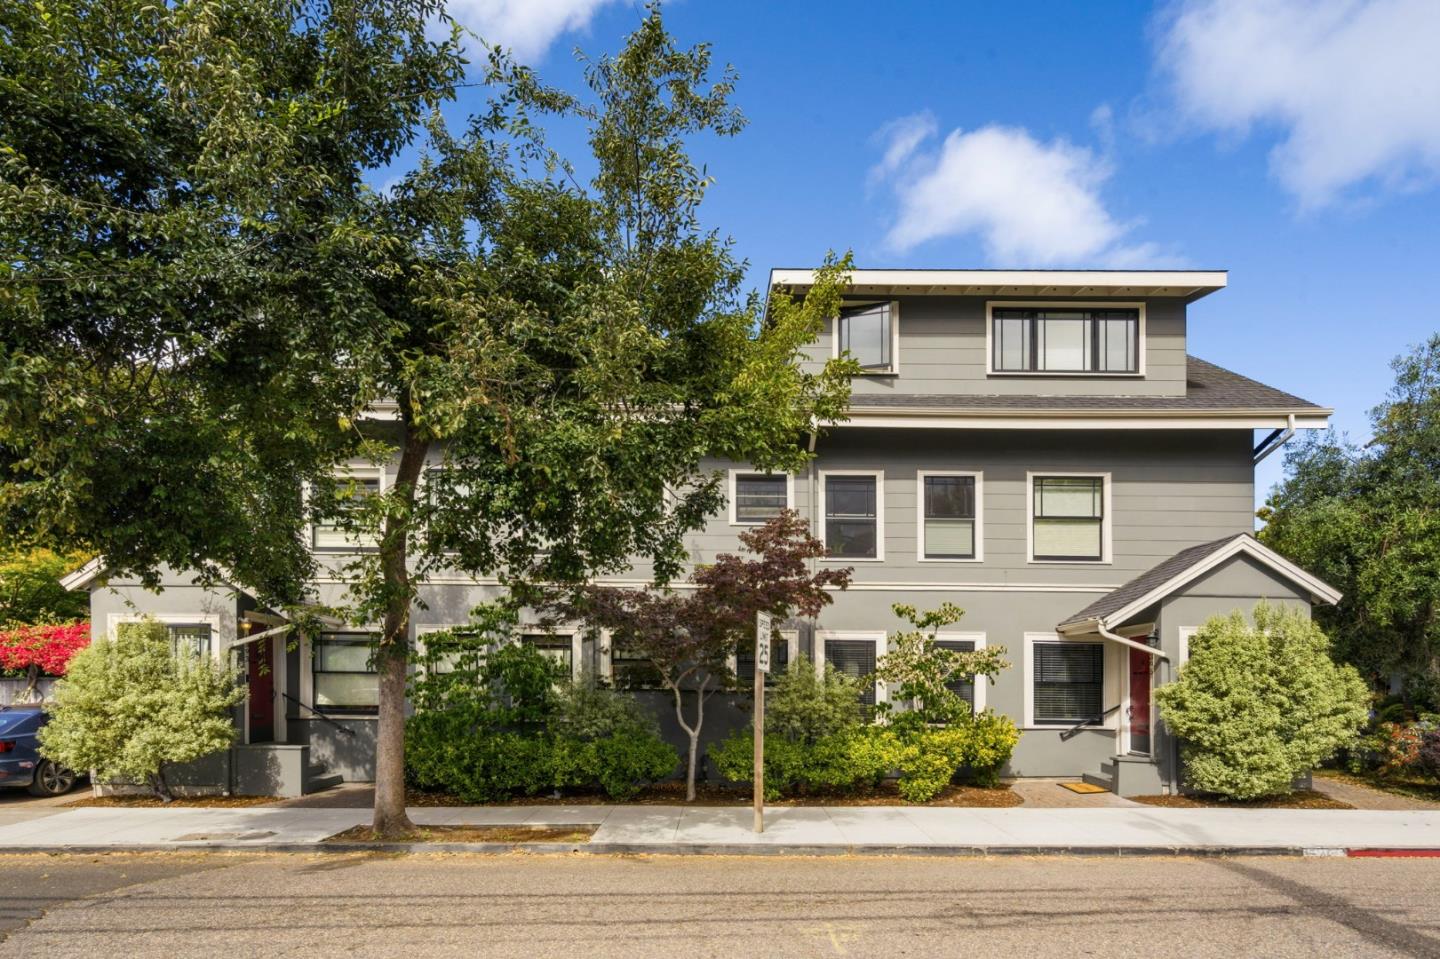 $849,000
Active
6395 Hillegass Avenue Oakland, California
2 Beds 1 Baths 862 SqFt
 $849,800
Active
4529 Capewood Terrace Fremont, California
3 Beds 2 Baths 1,242 SqFt 0.021 Acres
 $849,990
Active
7045 Coombsville Loop Dublin, California
2 Beds 2 Baths 1,514 SqFt
 $865,000
Active
7556 Silvertree Ln #20 Dublin, California
3 Beds 2 Baths 1,242 SqFt
 $875,000
Active
897 Tranquility Cir 7 Livermore, California
3 Beds 3 Baths 1,789 SqFt
 $875,000
Active
5361 Black Ave. 4 Pleasanton, California
3 Beds 2 Baths 1,690 SqFt 4.12 Acres
 $885,000
Active
4125 Amberwood Cir Pleasanton, California
2 Beds 2 Baths 1,190 SqFt 0.03 Acres
 $886,033
Active
4810 Dolcetto Common Livermore, California
3 Beds 3 Baths 1,585 SqFt
 $889,800
Active
2060 Briscoe Terrace Fremont, California
2 Beds 1 Baths 1,066 SqFt 0.028 Acres
 $895,000
Active
4324 Montgomery St B Oakland, California
3 Beds 2 Baths 1,058 SqFt 0.143 Acres
 $899,000
Active
1169 Hearst Ave B Berkeley, California
2 Beds 1 Baths 846 SqFt 0.019 Acres
 $899,000
Active
333 Basswood Cmn 8 Livermore, California
3 Beds 3 Baths 1,789 SqFt
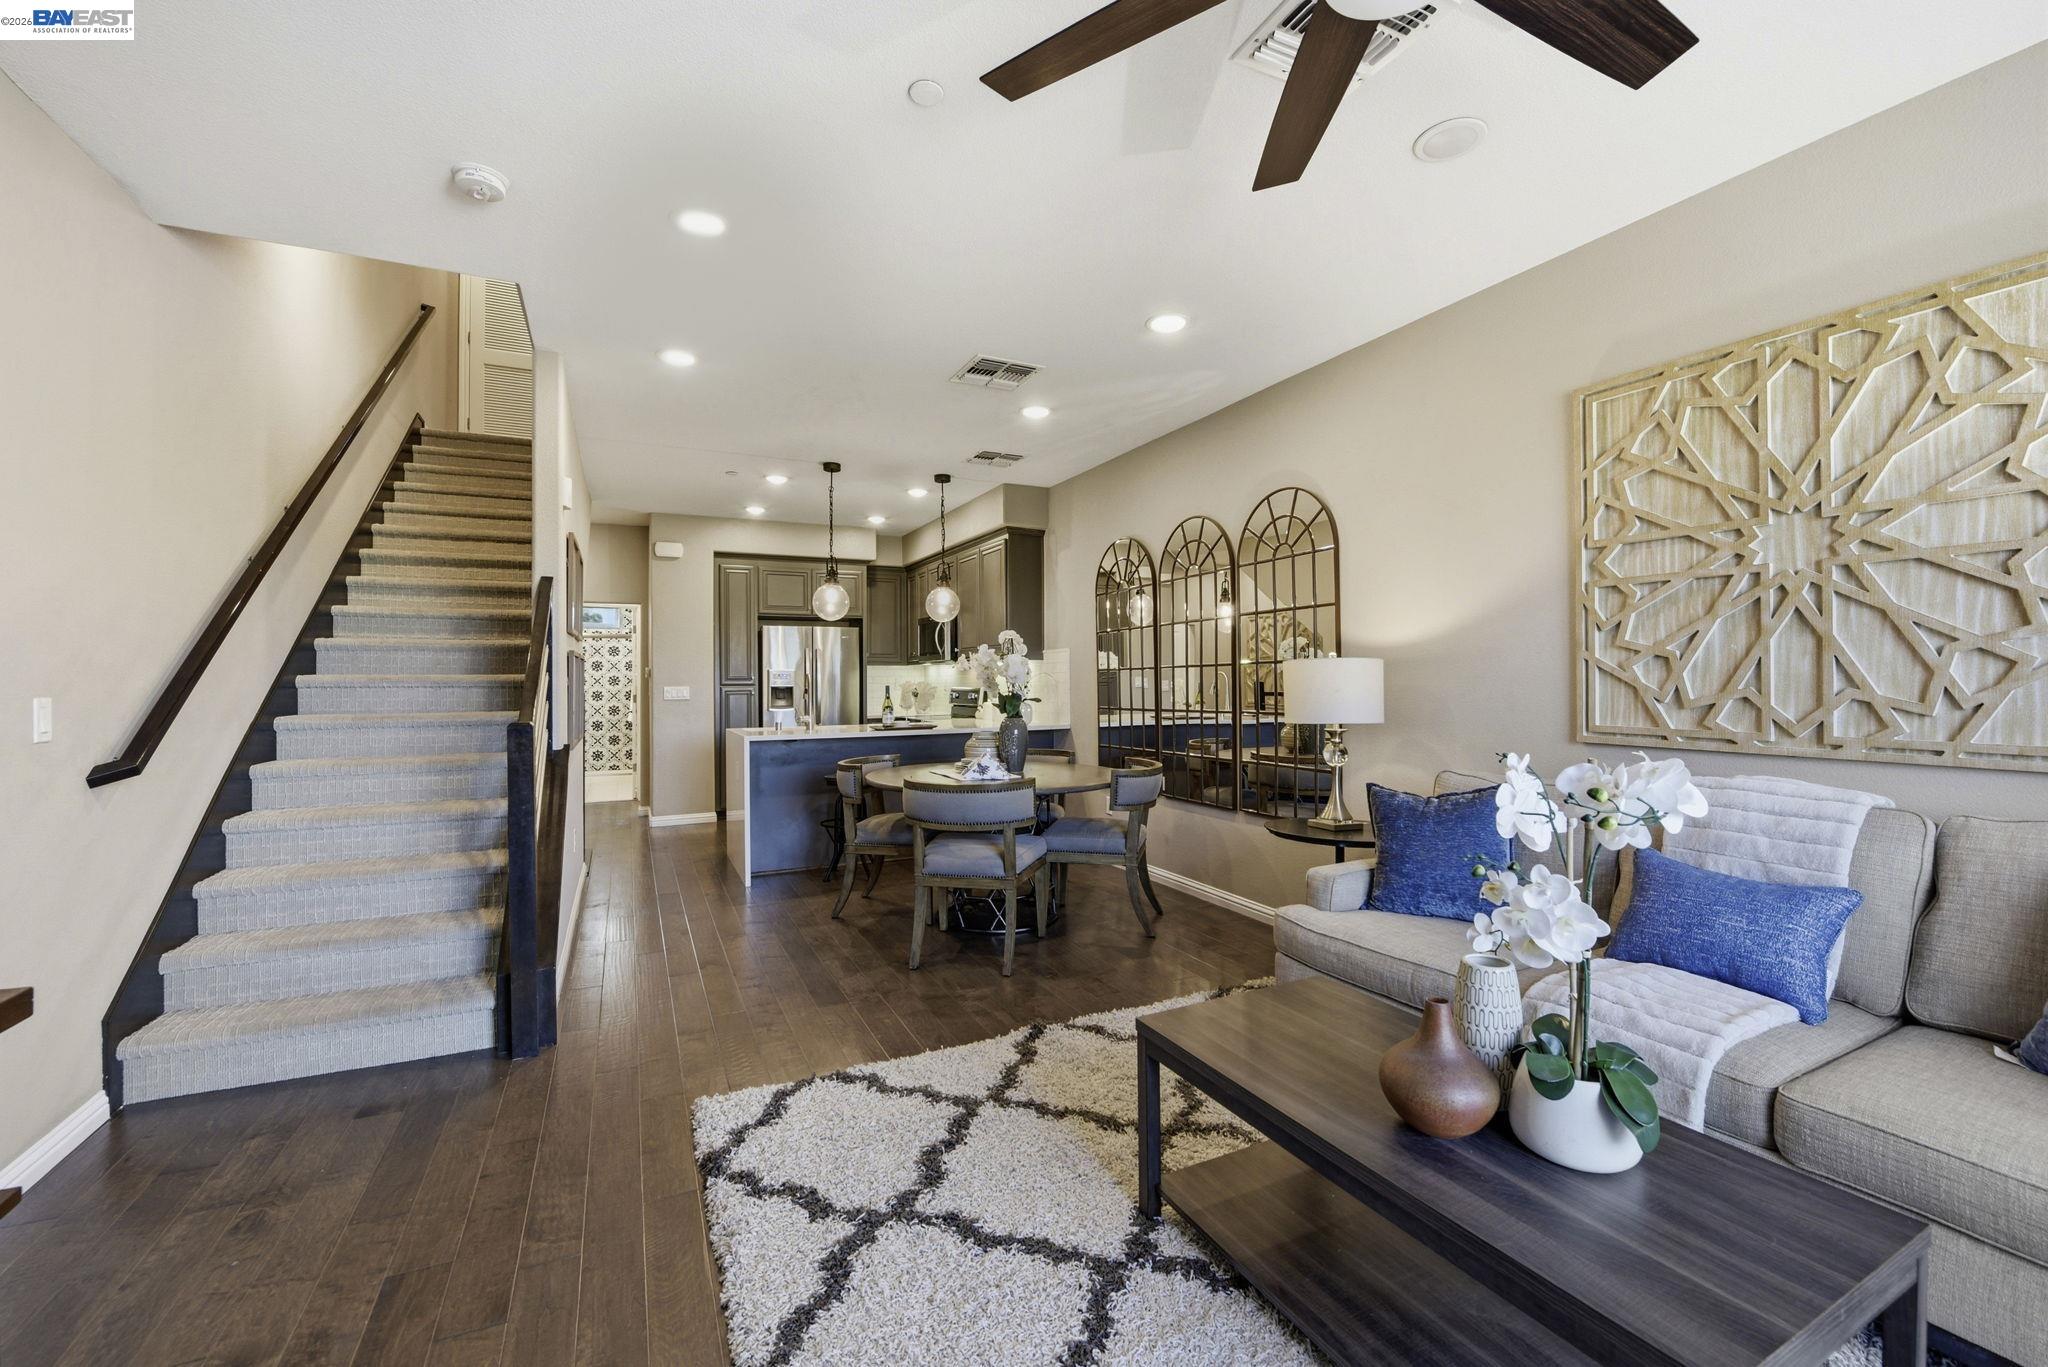 $1,049,000
Active
4119 Peralta Blvd Fremont, California
3 Beds 3 Baths 1,652 SqFt
 $975,000
Active
1815 Balsa St Alameda, California
3 Beds 3 Baths 1,727 SqFt 1.564 Acres
 $950,000
Active
259 Birch Creek Dr Pleasanton, California
3 Beds 2 Baths 1,848 SqFt
 $999,990
Active
7483 Stonedale Dr Pleasanton, California
3 Beds 2 Baths 1,500 SqFt 0.035 Acres
 $999,000
Active
3992 Scottfield St Dublin, California
3 Beds 3 Baths 1,949 SqFt
 $925,000
Active
1510 Corte Reina Cmn Livermore, California
3 Beds 2 Baths 1,840 SqFt 0.069 Acres
 $999,000
Active
4858 Swinford Ct Dublin, California
3 Beds 2 Baths 1,565 SqFt
 $1,095,000
Active
8544 Leeward Way Newark, California
4 Beds 3 Baths 2,109 SqFt 0.225 Acres
 $1,100,000
Active
2709 10Th St D Berkeley, California
2 Beds 1 Baths 1,495 SqFt 0.135 Acres
 $1,124,999
Active
5585 Holly Bay Avenue Dublin, California
4 Beds 3 Baths 2,192 SqFt
 $1,050,000
Active
3909 Eminence St Dublin, California
3 Beds 3 Baths 1,766 SqFt
 $1,049,000
Active
4071 Ghiotti Dr Pleasanton, California
3 Beds 2 Baths 1,503 SqFt 0.027 Acres
 $949,000
Active
2802 Tradewind Ct Alameda, California
3 Beds 2 Baths 1,506 SqFt
 $1,328,000
Active
1920 Willow St Alameda, California
4 Beds 3 Baths 2,322 SqFt 0.053 Acres
 $1,075,000
Active
37946 Bright Cmn Fremont, California
3 Beds 2 Baths 1,717 SqFt 0.043 Acres
 $979,000
Active
7981 Bellina St Dublin, California
4 Beds 2 Baths 1,701 SqFt
 $949,000
Active
9732 Seawind Way Newark, California
3 Beds 3 Baths 1,643 SqFt
 $999,800
Active
222 Corte San Pablo Fremont, California
3 Beds 2 Baths 1,242 SqFt 0.022 Acres
 $1,139,999
Active
3816 Pioneer Ter Fremont, California
3 Beds 3 Baths 1,399 SqFt 0.029 Acres
 $949,000
Active
2339 Kinetic Cmn 209 Fremont, California
2 Beds 2 Baths 1,608 SqFt 0.859 Acres
 $939,900
Active
1849 Arch Street A Berkeley, California
3 Beds 2 Baths 1,532 SqFt 0.101 Acres
 $1,149,000
Active
5420 Central Pkwy D Dublin, California
4 Beds 3 Baths 2,129 SqFt
 $1,249,900
Active
3765 Castro Valley Blvd Castro Valley, California
4 Beds 3 Baths 2,062 SqFt 0.047 Acres
 $1,068,000
Active
37457 Salt Grass Rd Newark, California
4 Beds 3 Baths 1,974 SqFt
 $1,200,000
Active
238 Paso Roble Cmn Fremont, California
3 Beds 2 Baths 1,431 SqFt
 $1,175,000
Active
5214 Riverdale Ct Pleasanton, California
4 Beds 2 Baths 2,119 SqFt 0.061 Acres
 $999,800
Active
3649 Branding Iron Pl Dublin, California
4 Beds 4 Baths 2,015 SqFt
 $1,195,000
Active
611 Harbor Rd Alameda, California
2 Beds 2 Baths 1,602 SqFt 4.864 Acres
 $925,000
Active
987 Independence Dr Alameda, California
2 Beds 2 Baths 1,443 SqFt 0.334 Acres
 $1,095,000
Active
48 Invincible Ct F19 Alameda, California
2 Beds 3 Baths 1,608 SqFt 0.621 Acres
 $1,050,604
Active
4707 Marengo Common Livermore, California
4 Beds 3 Baths 2,094 SqFt
 $1,174,000
Active
5740 Belleza Dr Pleasanton, California
4 Beds 3 Baths 1,928 SqFt 0.031 Acres
 $950,000
Active
7445 Rolling Hills Cir Dublin, California
3 Beds 2 Baths 1,566 SqFt 0.047 Acres
 $1,199,990
Active
37433 Fremont Boulevard Fremont, California
3 Beds 3 Baths 1,657 SqFt
 $1,299,990
Active
37425 Fremont Boulevard Fremont, California
3 Beds 3 Baths 1,710 SqFt
 $1,099,024
Active
37437 Fremont Boulevard Fremont, California
3 Beds 3 Baths 1,394 SqFt
 $908,675
Active
37408 Hazel Terrace Fremont, California
2 Beds 2 Baths 1,165 SqFt
 $899,000
Active
37523 Shelter Road Newark, California
3 Beds 2 Baths 1,490 SqFt
 $1,099,888
Active
34823 Awning Terrace Fremont, California
2 Beds 2 Baths 1,437 SqFt
 $907,294
Active
37409 Currant Terrace Fremont, California
2 Beds 2 Baths 1,165 SqFt
 $1,074,990
Active
37431 Fremont Boulevard Fremont, California
2 Beds 3 Baths 1,394 SqFt
 $900,000
Active
1746 Pedrozzi Common Livermore, California
4 Beds 3 Baths 1,929 SqFt 0.023 Acres
 $1,230,000
Active
35 Catania Common Fremont, California
3 Beds 2 Baths 1,799 SqFt
 $998,000
Active
3858 Development 1000 Fremont, California
2 Beds 2 Baths 1,326 SqFt
 $989,000
Active
2337 Royal Ann Drive Union City, California
3 Beds 2 Baths 1,503 SqFt
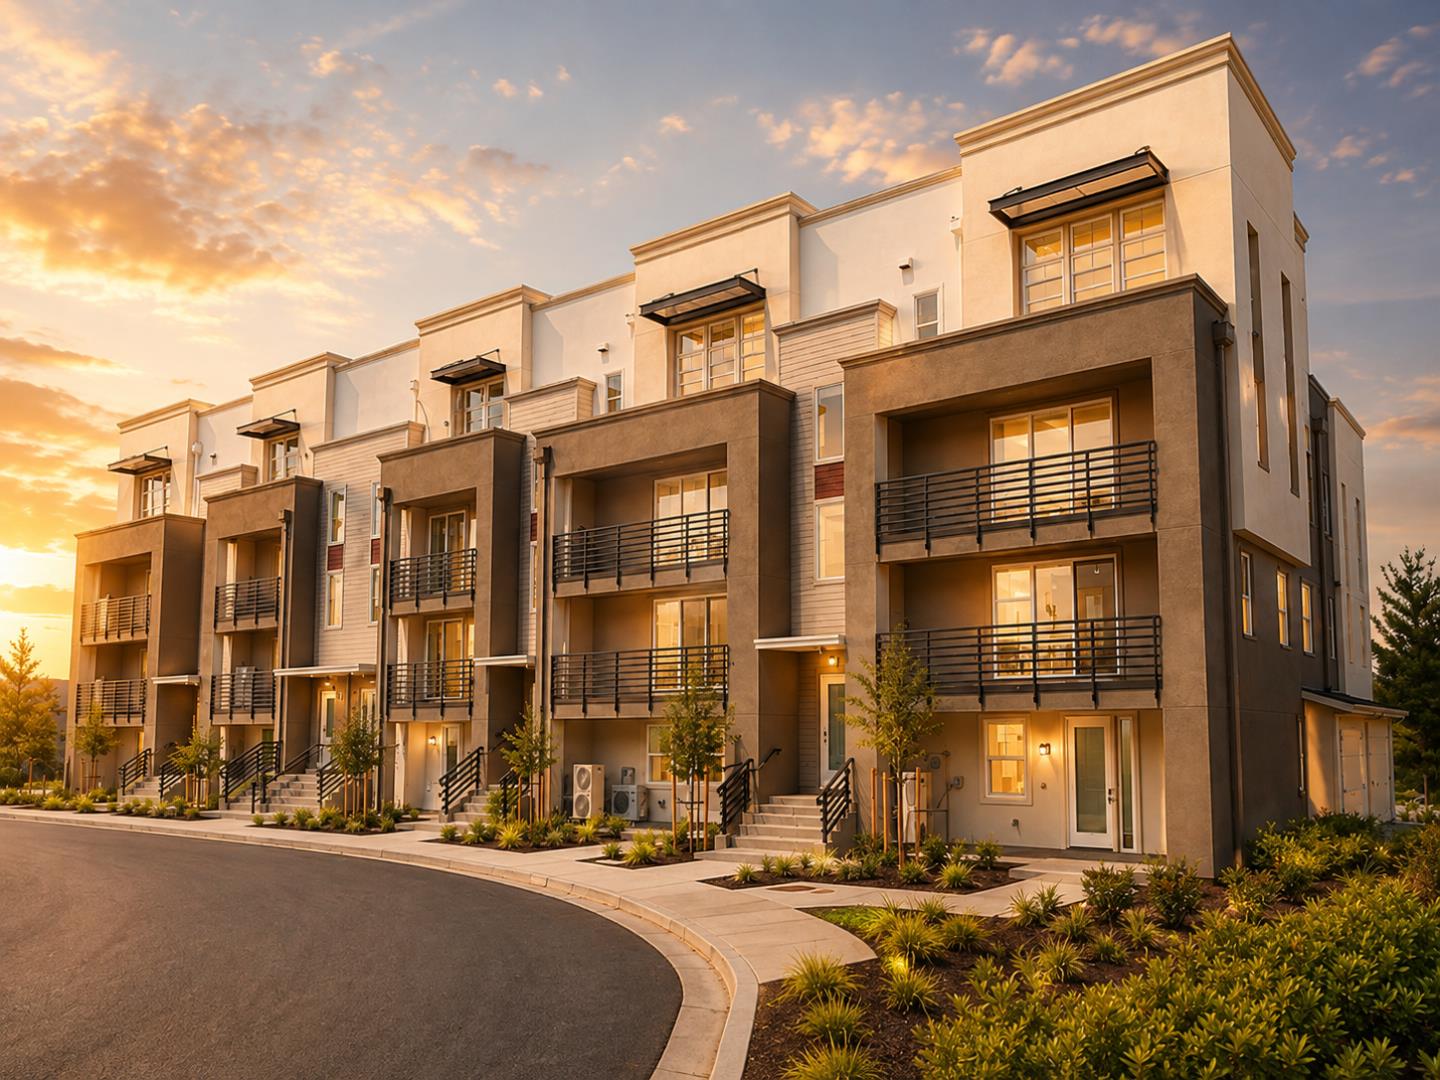 $1,198,000
Active
5456 Arnold Road Dublin, California
4 Beds 3 Baths 2,745 SqFt 0.063 Acres
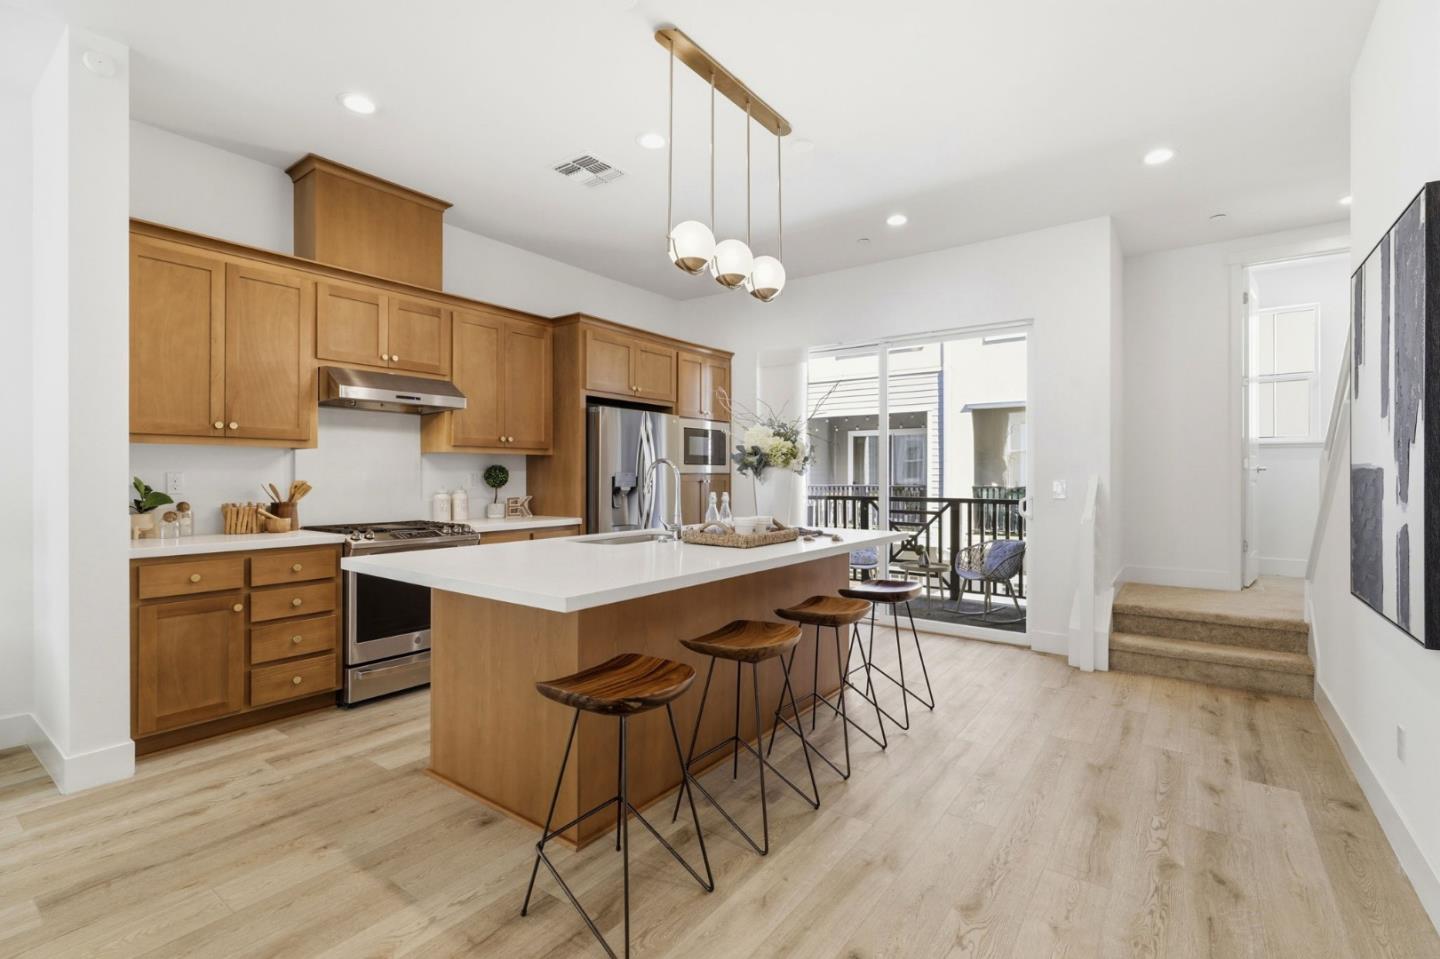 $1,120,000
Active
37309 Suncrest Street Newark, California
3 Beds 3 Baths 1,871 SqFt
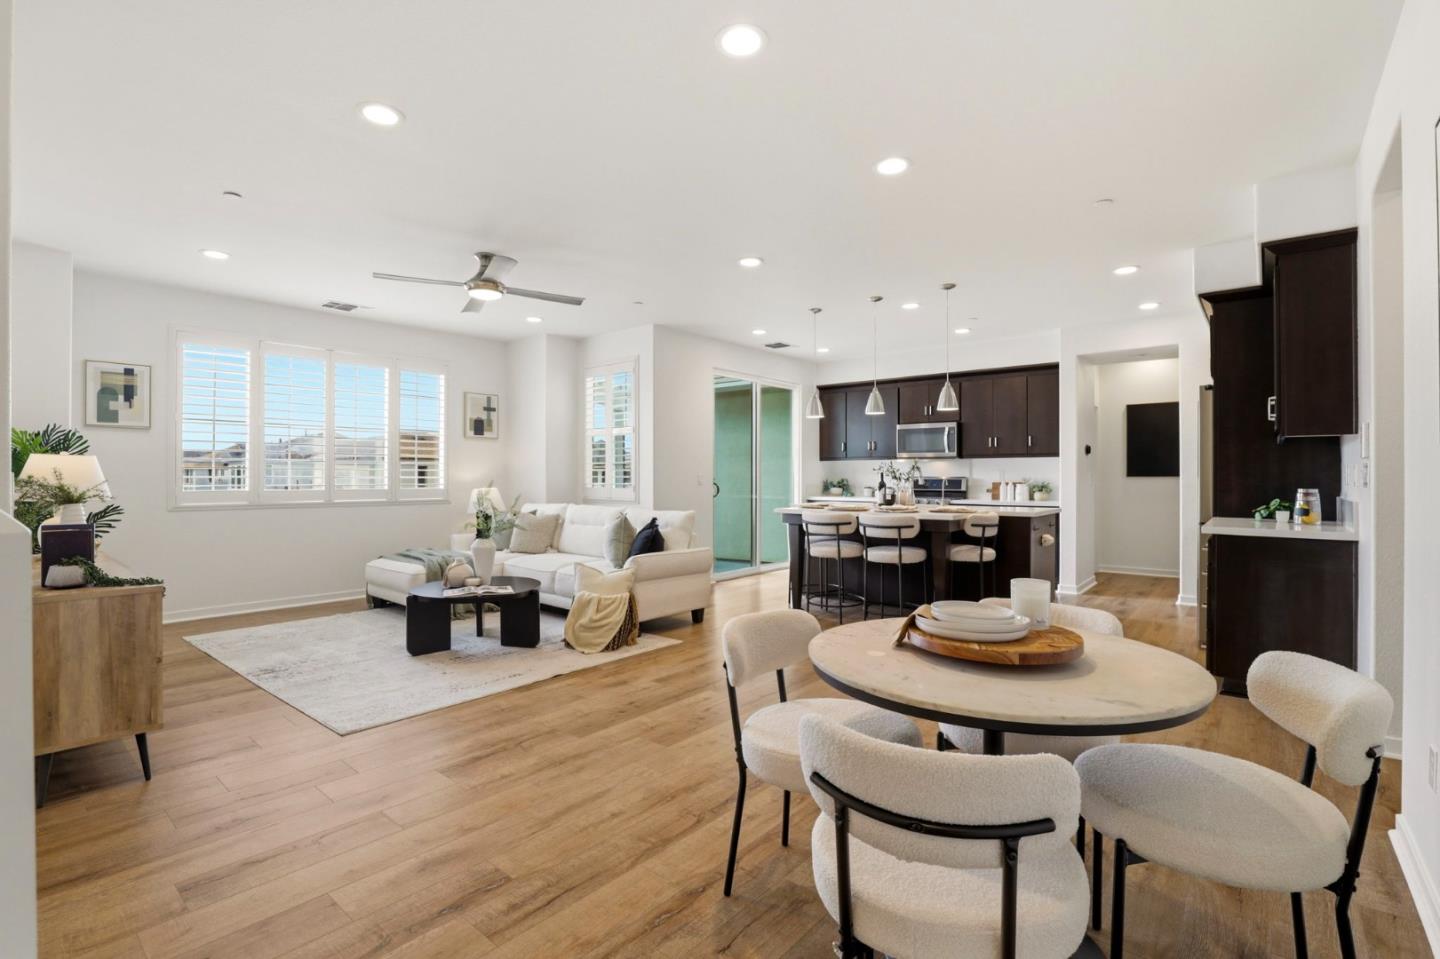 $915,000
Active
37665 Breakers Road Newark, California
3 Beds 2 Baths 1,490 SqFt 0.348 Acres
 $990,000
Active
3891 Vanguard Common 1004 Fremont, California
2 Beds 2 Baths 1,326 SqFt
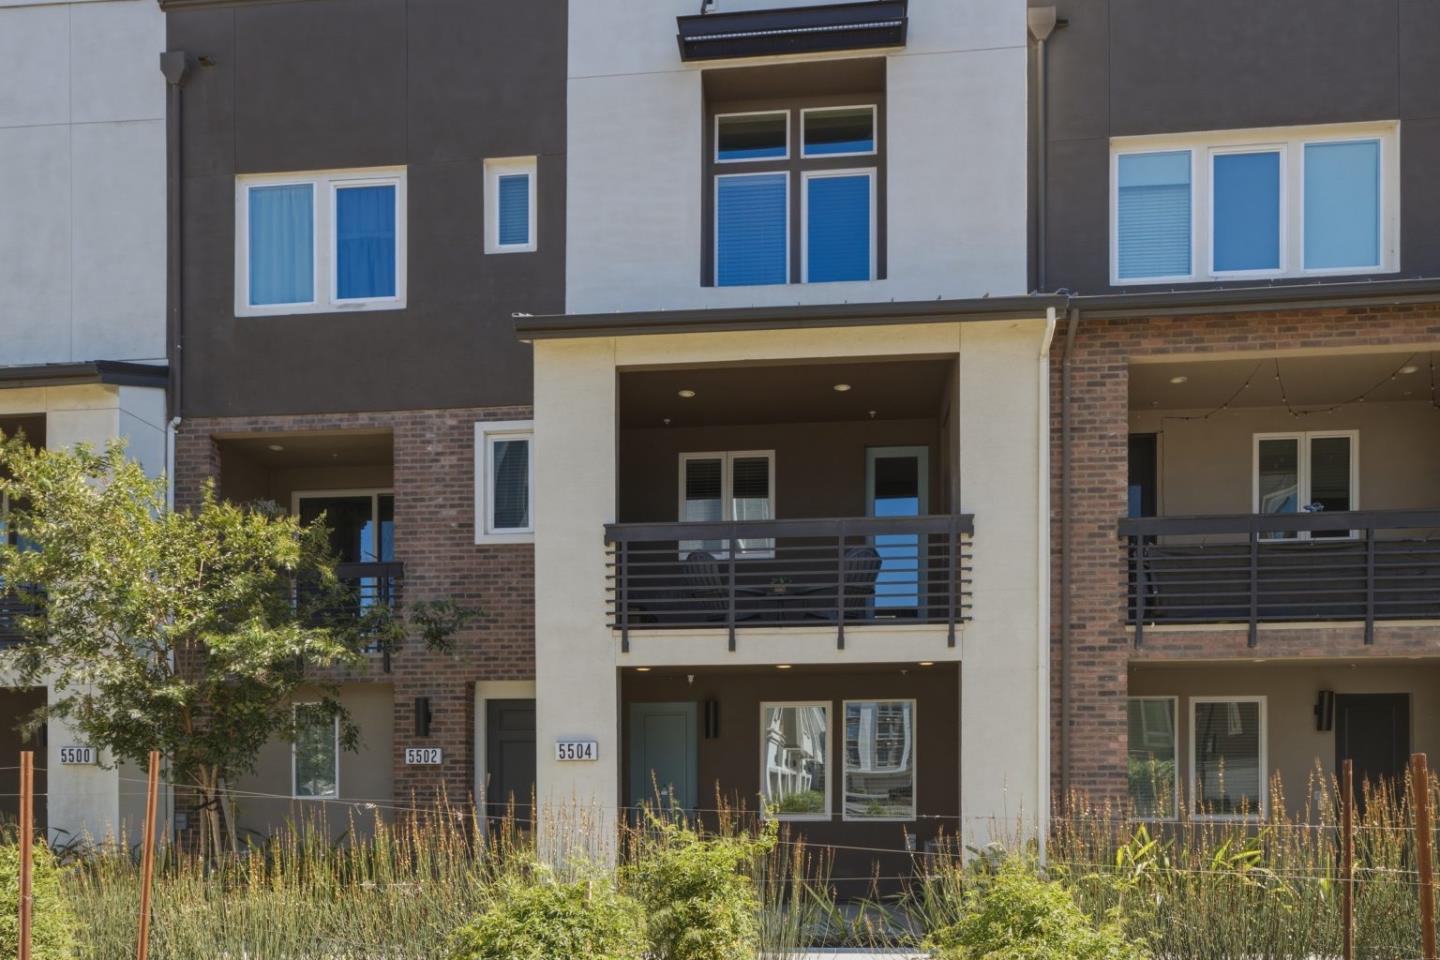 $1,050,000
Active
5504 El Dorado Lane Dublin, California
3 Beds 3 Baths 1,719 SqFt
 $1,348,000
Active
3310 Giovanni Way Dublin, California
5 Beds 4 Baths 2,833 SqFt
 $925,000
Active
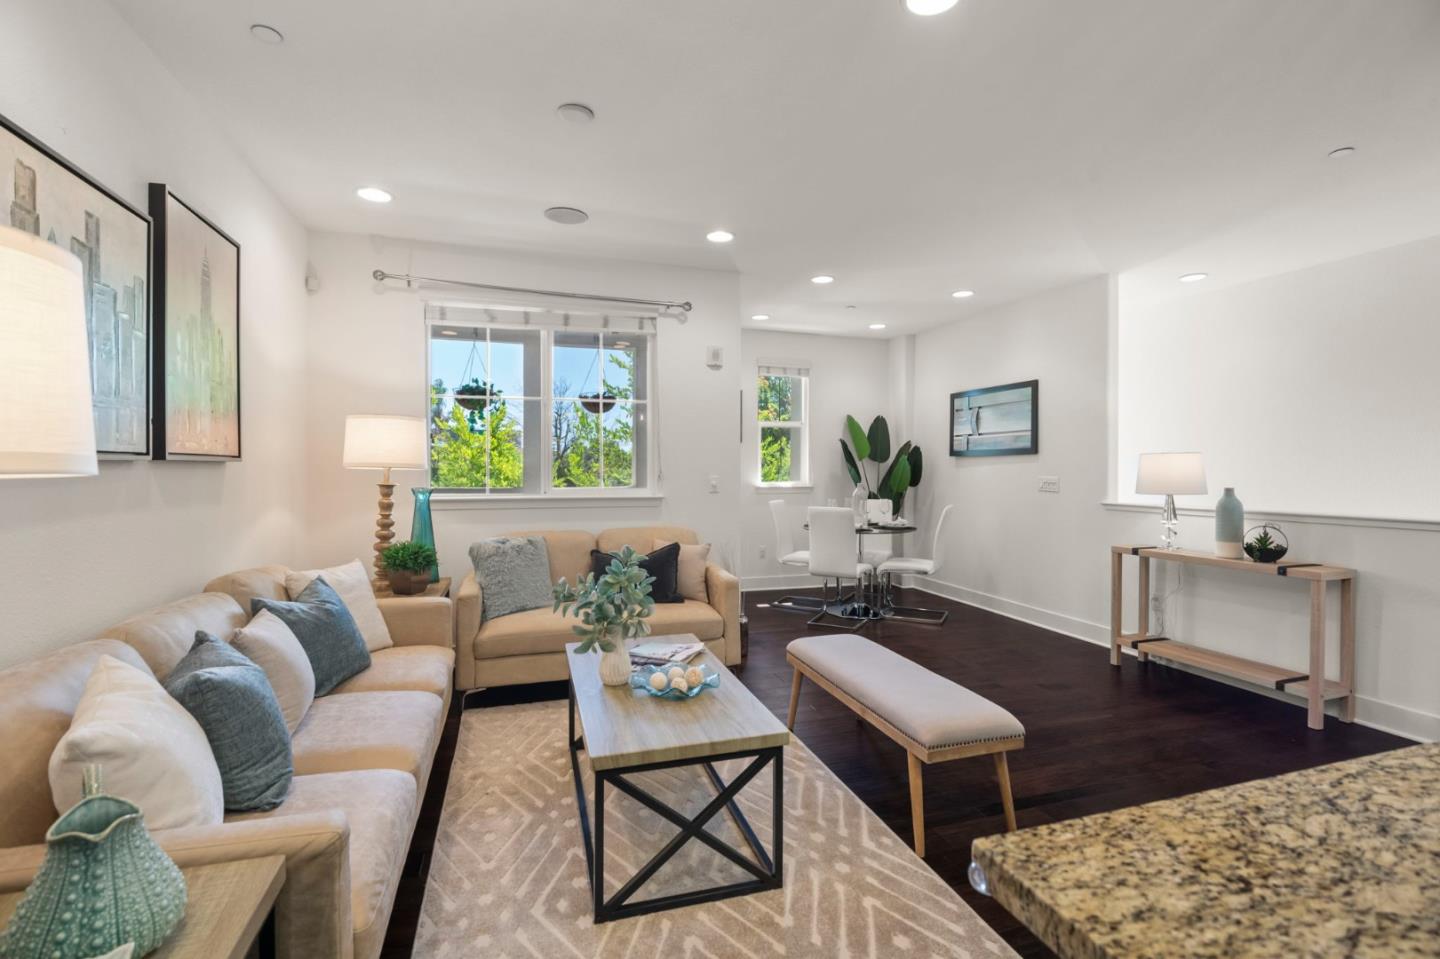
37605 Pimento Common Fremont, California
2 Beds 2 Baths 1,161 SqFt
 $1,249,000
Active
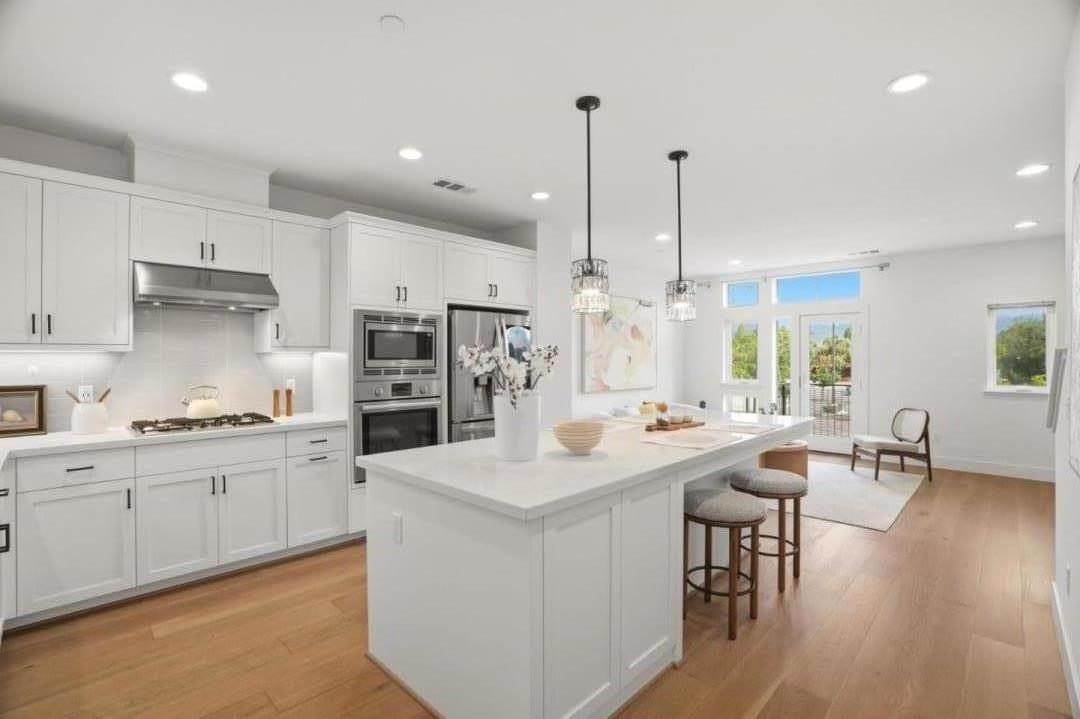
39185 State Street Fremont, California
4 Beds 4 Baths 1,790 SqFt